No Result
View All Result
  • Login
Monday, September 21, 2026
FeeOnlyNews.com
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading
No Result
View All Result
FeeOnlyNews.com
No Result
View All Result
Home Money

The “Super Catch-Up” Math: How to Add $143,000 to Your Nest Egg in 4 Years

by FeeOnlyNews.com
6 months ago
in Money
Reading Time: 4 mins read
A A
0
The “Super Catch-Up” Math: How to Add 3,000 to Your Nest Egg in 4 Years
Share on FacebookShare on TwitterShare on LInkedIn


Image Source: Shutterstock

When retirement is just around the corner, many people start to worry that they didn’t save enough early on in their working years. But that doesn’t mean it is too late. A newer retirement rule is giving people in their early 60s a chance to catch up. Now, thanks to changes from the SECURE 2.0 law, workers between the ages of 60 and 63 can make higher retirement contributions than ever before. If used strategically, this opportunity could help some workers add more than $143,000 to their retirement accounts in just four years. Here’s how you can stack up serious savings over the next four years.

What the Super Catch-Up Contribution Actually Is

The super catch-up contribution is a special retirement savings rule for workers ages 60 through 63. Under this provision, eligible employees can contribute significantly more to their workplace retirement plans than standard limits allow. For example, in 2025, workers can defer up to $23,500 into a 401(k) plan, and those aged 60–63 can add an additional $11,250 catch-up amount.

That means the total employee contribution could reach $34,750 for that year. The rule applies to common workplace plans like 401(k), 403(b), and government 457(b) plans. The super catch-up contribution gives older workers a rare opportunity to dramatically accelerate retirement savings late in their careers.

Why the Age 60–63 Window Is So Powerful

The super catch-up contribution only applies for a short window that falls between the ages of 60, 61, 62, and 63. Congress intentionally targeted this age group because earnings often peak during these years. Many workers also have fewer expenses once children leave home or mortgages shrink. This combination creates a unique opportunity to increase savings dramatically. The law allows the catch-up amount to reach the greater of $10,000 or 150% of the regular catch-up contribution limit. In 2025, that formula resulted in the higher $11,250 super catch-up amount.

The Simple Math Behind the $143,000 Boost

The headline number (about $143,000) comes from maximizing contributions during the four-year super catch-up window. If a worker contributes $34,750 annually from ages 60 through 63, the total contribution equals $139,000. Add modest investment growth during those years, and the total can easily approach or exceed $143,000.

This figure only reflects employee contributions and potential short-term growth. Employer matches could push the number even higher in some cases. That’s why financial planners often call the super catch-up contribution one of the most powerful late-career retirement tools available today.

Your Employer’s Plan Must Offer the Feature

Not every retirement plan automatically includes the super catch-up contribution. Employers must update their retirement plans to offer the enhanced limits. Some companies have already implemented the change, while others are still updating plan documents.

If the feature isn’t available yet, your plan may still cap catch-up contributions at the regular limit. Experts recommend checking with HR or your plan administrator to confirm eligibility. If your employer offers it, the super catch-up contribution can significantly expand your savings capacity.

New Roth Rules May Affect High Earners

Another important rule is coming for higher-income workers. Under SECURE 2.0, individuals earning more than $145,000 from their employer may need to make catch-up contributions to a Roth account instead of a traditional pre-tax account beginning in 2026.

This means the contributions are taxed upfront, but withdrawals may be tax-free later. While this removes the immediate tax deduction, it can provide valuable tax-free income in retirement. For some savers, the Roth requirement may actually strengthen long-term tax planning.

Many Workers Still Don’t Take Advantage of Catch-Ups

Despite the benefits, many eligible workers fail to use catch-up contributions at all. Surveys of retirement plans show that only a small percentage of workers max out these extra contributions each year. Some people simply aren’t aware that the option exists. Others feel they cannot afford higher savings late in their careers.

However, financial planners often encourage boosting contributions even partially during the catch-up window. Even smaller increases can produce meaningful growth over time. The super catch-up contribution gives people who started saving late a valuable second chance.

Combine Catch-Ups with Other Retirement Strategies

The super catch-up contribution works even better when combined with other retirement strategies. Workers over 50 can also contribute catch-up amounts to IRAs and Health Savings Accounts. Diversifying savings across multiple tax-advantaged accounts can strengthen retirement security.

Additionally, some investors use this period to rebalance portfolios or reduce high-interest debt before retirement. Combining these moves can significantly improve financial readiness. When used strategically, the super catch-up contribution becomes part of a broader retirement acceleration plan.

The Four-Year Window That Can Transform Your Retirement Savings

Retirement planning often feels like a marathon, but sometimes a final sprint can make a big difference. The super catch-up contribution offers workers in their early 60s a rare chance to boost savings dramatically in just four years. By maximizing contributions and allowing even modest investment growth, many workers could add over $143,000 to their retirement accounts.

While the opportunity is limited to a short age window, it can be incredibly powerful for those who take advantage of it. For workers approaching retirement, understanding this rule may be one of the most important financial moves of the decade. A few strategic years of higher contributions could significantly strengthen long-term financial security.

If you’re approaching retirement, would you consider maximizing the super catch-up contribution to boost your savings?

What to Read Next

5 Harmless Hobbies That Are Secretly Draining Your Nest Egg

The Secret Retirement Move That Could Add $100K to Your Nest Egg

The Rise of Multigenerational Suites: Why More New Homes Now Include a “Granny Flat”

Turning 60 Soon? The Retirement Catch-Up Strategy Many Savers Overlook

Catch-Up Contributions Are Shifting in 2026 — The Retirement-Savings Detail High Earners Can’t Ignore


Source link

Tags: AddcatchupEggMathNestSuperYears
ShareTweetShare
Previous Post

New IRS MATH Act: What It Means for Error Notices and Your Right to Challenge Them

Next Post

The Hidden Risk in Aging‑in‑Place Gadgets: Why Some Amazon Products Don’t Meet Safety Standards

Related Posts

6 Part-Time Jobs Retirees Can Explore Before the Holiday Hiring Rush

6 Part-Time Jobs Retirees Can Explore Before the Holiday Hiring Rush

by FeeOnlyNews.com
August 7, 2026
0

The weeks before the holiday hiring rush can be a surprisingly good time for retirees to decide whether a little...

Medicare Deadlines New Retirees Should Put on the Calendar Before Leaving Work

Medicare Deadlines New Retirees Should Put on the Calendar Before Leaving Work

by FeeOnlyNews.com
August 7, 2026
0

A 65-year-old retiring in November may have a completely different Medicare timeline from a 68-year-old leaving an employer health plan...

8 Side Effects of Aging That No One Prepares You For

8 Side Effects of Aging That No One Prepares You For

by FeeOnlyNews.com
August 7, 2026
0

Aging is often portrayed as a graceful journey filled with wisdom, leisure, and newfound freedom. While those aspects can certainly...

Stock news for investors: Quarterly earnings from Telus, Shopify, BCE, and more

Stock news for investors: Quarterly earnings from Telus, Shopify, BCE, and more

by FeeOnlyNews.com
August 6, 2026
0

The company reported a loss attributable to common shareholders of $1.8 billion or $1.17 per share for the quarter ended...

The world’s largest corporate holder of Bitcoin has been selling—should you be concerned?

The world’s largest corporate holder of Bitcoin has been selling—should you be concerned?

by FeeOnlyNews.com
August 6, 2026
0

While selling BTC is not alarming in itself, it seems to go against Executive Chairman Micheal Saylor’s public image as...

7 Warning Signs an Older Adult May Be Under Financial Pressure

7 Warning Signs an Older Adult May Be Under Financial Pressure

by FeeOnlyNews.com
August 6, 2026
0

It often starts with what seems like a harmless favor. A relative offers to help pay bills online. A new...

Next Post
The Hidden Risk in Aging‑in‑Place Gadgets: Why Some Amazon Products Don’t Meet Safety Standards

The Hidden Risk in Aging‑in‑Place Gadgets: Why Some Amazon Products Don’t Meet Safety Standards

Growth Prospects Backed by Analyst Upgrades

Growth Prospects Backed by Analyst Upgrades

  • Trending
  • Comments
  • Latest
MEXC Lists Ondo Yield Asset As Tokenized Treasury Demand Grows

MEXC Lists Ondo Yield Asset As Tokenized Treasury Demand Grows

July 3, 2026
Delek Logistics Partners Reports alt=

Delek Logistics Partners Reports $0.54 EPS for Q2 FY26

August 5, 2026
Ship and Debit Automation: A 2026 Guide to Margin Protection

Ship and Debit Automation: A 2026 Guide to Margin Protection

July 30, 2026
China threatens retaliation against U.S. humanoid robot ban, says it ‘severely damages’ relations

China threatens retaliation against U.S. humanoid robot ban, says it ‘severely damages’ relations

July 29, 2026
The AI Race With China Is a Lie Told by Big Tech to Justify the Data Center Invasion

The AI Race With China Is a Lie Told by Big Tech to Justify the Data Center Invasion

July 27, 2026
Here’s When Amazon’s ROI Will Pull Ahead of Microsoft’s in the AI Cloud Spend War

Here’s When Amazon’s ROI Will Pull Ahead of Microsoft’s in the AI Cloud Spend War

July 20, 2026
Advanced Micro Devices (AMD) Price Prediction: How Much a ,000 Investment Could Be Worth by 2031

Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031

0
Cities holding up to 3 million people found under Amazon rain forest

Cities holding up to 3 million people found under Amazon rain forest

0
Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

0
Bybit Uses Tokenised Equities as Underlyings for Structured Yield

Bybit Uses Tokenised Equities as Underlyings for Structured Yield

0
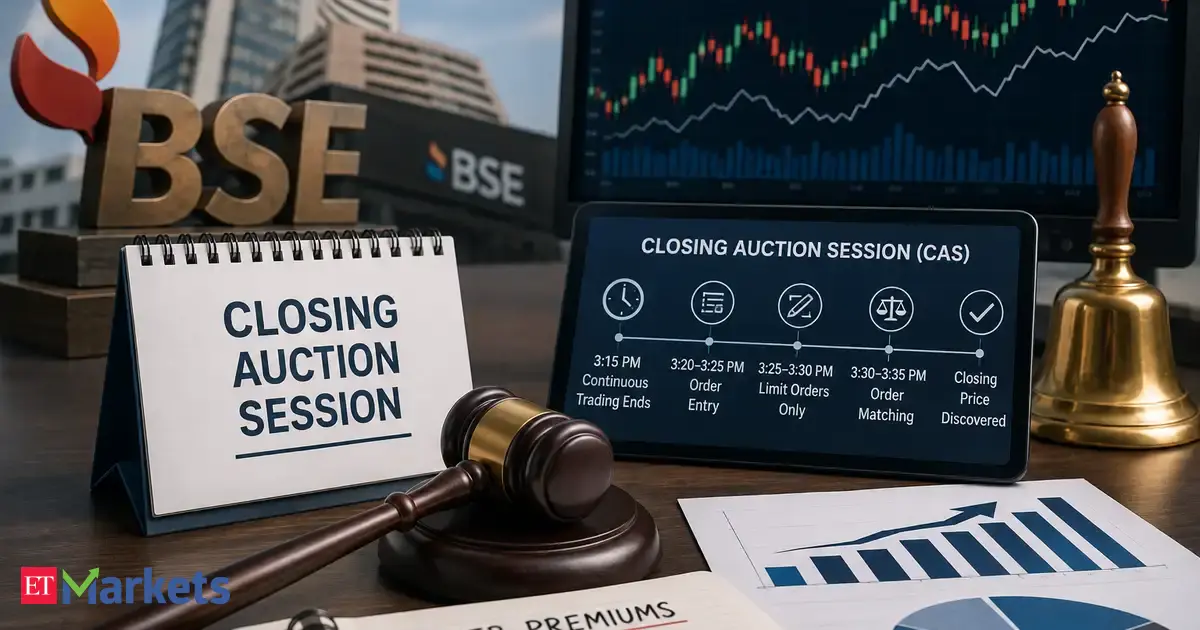
Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

0
Vaxart outlines Phase IIb COVID-19 top line data in first half of 2027 backed by BARDA funding (OTCMKTS:VXRT)

Vaxart outlines Phase IIb COVID-19 top line data in first half of 2027 backed by BARDA funding (OTCMKTS:VXRT)

0
Advanced Micro Devices (AMD) Price Prediction: How Much a ,000 Investment Could Be Worth by 2031

Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031

August 8, 2026
Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

August 8, 2026
Vanguard Chief Economist: AI and jobs, still in an ATM phase

Vanguard Chief Economist: AI and jobs, still in an ATM phase

August 8, 2026
Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

August 8, 2026
Democrats’ Affordability Message Misses a Key Expense—Student Debt

Democrats’ Affordability Message Misses a Key Expense—Student Debt

August 8, 2026
Banks or NBFCs? DSP’s Preethi R S explains where she sees the best opportunities

Banks or NBFCs? DSP’s Preethi R S explains where she sees the best opportunities

August 8, 2026
FeeOnlyNews.com

Get the latest news and follow the coverage of Business & Financial News, Stock Market Updates, Analysis, and more from the trusted sources.

CATEGORIES

  • Business
  • Cryptocurrency
  • Economy
  • Financial Planning
  • Investing
  • Market Analysis
  • Markets
  • Money
  • Personal Finance
  • Startups
  • Stock Market
  • Trading

LATEST UPDATES

  • Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031
  • Republican Party Displacement | Mises Institute
  • Vanguard Chief Economist: AI and jobs, still in an ATM phase
  • Our Great Privacy Policy
  • Terms of Use, Legal Notices & Disclaimers
  • About Us
  • Contact Us

Copyright © 2022-2024 All Rights Reserved
See articles for original source and related links to external sites.

Welcome Back!

Sign In with Facebook
Sign In with Google
Sign In with Linked In
OR

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In
No Result
View All Result
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading

Copyright © 2022-2024 All Rights Reserved
See articles for original source and related links to external sites.