Savers might want to take a second look at I Bonds, if they’re rattled by the latest downturn in the stock market and surge in inflation.
Anyone who drives by a gas station sees how prices at the pump skyrocketed, and it’s possible that inflation will heat up even more depending on how the Iran war unfolds. The United States and Israel launched unexpected, widespread airstrikes against Iran on Feb. 28.
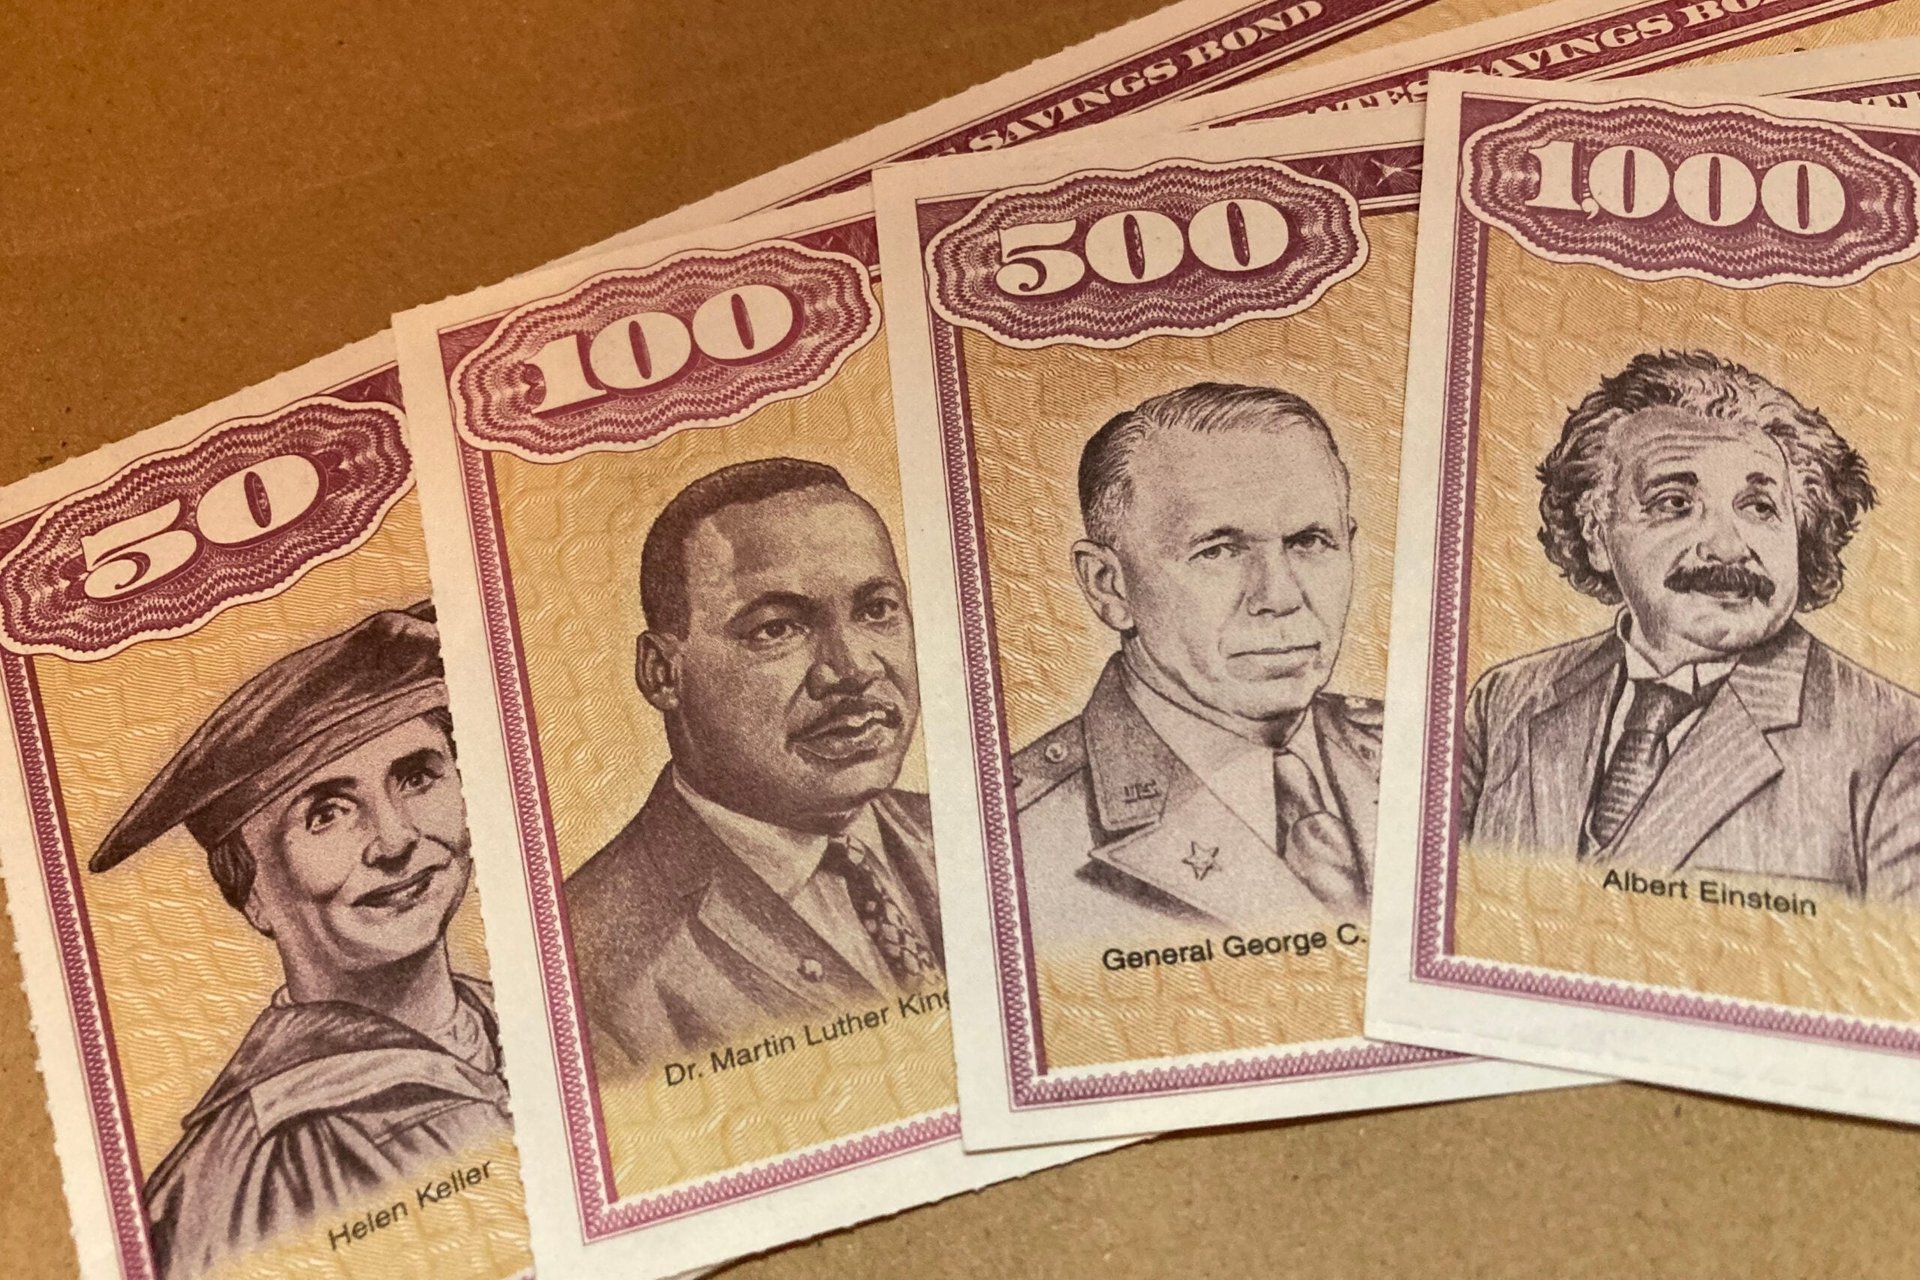
The “I” in Series I savings bonds stands for inflation. The idea is to use I Bonds to protect savings against inflation. The composite interest rate on I Bonds can go up or down every six months after you bought the bond, based on the shift in inflation.
I Bonds can be used as part emergency savings, part conservative holdings for investors who want to guard some of their portfolio from dramatic downturns in the stock market.
Inflation Hit Its Hottest Point in 2 Years
For months, I’ve heard from savers who talked more about dumping the once high-paying I Bonds bought a few years ago than buying new ones. Inflation, after all, had fallen significantly since peaking at 9.1% in June 2022 — the highest level in 40 years.
And that story line probably would have continued — if we didn’t get the latest inflation shock.
Given the latest surge in inflation, though, savers might reconsider selling off those I Bonds just yet. And if you need to unload some I Bonds, perhaps to cover bills, you will want to take extra care to make sure that you’re dumping the right bonds.
“People were definitely losing interest in I Bonds,” according to David Enna, who founded Tipswatch.com and regularly tracks inflation-adjusted government bonds.
All of that has changed in recent weeks, as inflation took off.
We got our first glimpse at the latest inflation picture on Friday, April 10, when the U.S. Bureau of Labor Statistics released the Consumer Price Index for March.
Over the last 12 months, consumer prices rose rather sharply to 3.3%. By contrast, the CPI rose 2.4% year-over-year in February.
Gasoline prices rose 18.9% in March over the past 12 months; fuel oil prices rose 44.2% year-over-year, according to the U.S. Bureau of Labor Statistics report issued April 10.
Month-to-month gasoline prices shot up 21.2%.
This sudden spike in inflation — and concerns about future price hikes on all sorts of goods — will soon give the inflation-indexed U.S. savings bonds a bit of a boost.
We’re talking about an estimated annualized rate of 4.26% that would apply for the first six months if you buy an I Bond in May through October, Enna said.
All I Bonds will benefit from an inflation-related change in their rates, too, in the months ahead.
I Bond rates soared and generated so much excitement in 2022, for example, that the TreasuryDirect.gov website even experienced intermittent slowdowns during a last-minute rush to buy I Bonds.
I Bonds bought in November 2022 through April 2023 had a 6.89% annualized rate. That rate applied for the first six months after the Series I Savings Bond is purchased. Those same bonds, which have a 0.4% fixed rate, currently have an annualized rate of 3.53% for six months.
Those who keep a close eye on I Bonds, like Enna, know that the March CPI, which is released in April, typically provides an essential piece of the puzzle for estimating the new rate that will apply to I Bonds bought from May through October.
“March inflation marks the end of a six-month string that will reset the I Bond’s variable rate on May 1,” Enna wrote recently. He noted that the new I Bond rate that begins in May will be based on non-seasonally-adjusted inflation for the months of October 2025 to March 2026.
New rates are announced every May 1 and Nov. 1 for savings bonds.
Why I Bond Rates Are Heading Higher
I Bonds have two components: a fixed rate that remains with the 30-year life of the savings bond and a variable rate that adjusts each six months after you bought the I Bond. Buy an I Bond in June and the variable rate will adjust in December.
Before the Iran war began in late February, Enna didn’t have big expectations for I Bond rates. In fact, he expected a decent drop in interest rates for I Bonds.
Before the Iran war, Enna said he would have confidently told savers that the variable rate for I Bonds was likely to fall on May 1 to about 2% from the current 3.12%. That variable rate matters to anyone who has I Bonds, no matter when they were bought.
And, again before the war, he said, the Treasury was likely to tinker with the fixed rate, too, perhaps dropping to 0.8% from the current 0.9%. That fixed rate applies to the life of the 30-year bond.
If those estimates proved true, Enna said, the composite rate for I Bonds issued from May through October would have been about 2.81%, down from the current 4.03%.
“After the war broke out, real yields went back up quite a bit,” Enna said.
“Inflation, obviously, was very high. That pushed all these numbers up.”
Now, Enna predicts that the I Bond’s new inflation-adjusted variable rate will be 3.34%, up from the current 3.12%. He’s anticipating a composite rate of 4.26% if the fixed rate remains at 0.9%, which he now expects it will, for I Bonds bought from May through October — the same as the fixed rate for I Bonds bought from November 2025 through April 2026.
All I Bonds will eventually get the variable annualized rate of 3.34% for six months. When the new variable rate starts for individual savers will depend on the original month when they bought the bond.
“Everybody wants to get I Bonds now. The question is just when,” Enna said.
Enna maintains that many people underestimate how well I Bonds can work for some of their savings, particularly emergency savings.
“That cash is sitting there, ready to use, but always moving higher with inflation. This is a super-safe investment,” Enna said.
How Do You Buy I Bonds?
Each calendar year, savers can set aside up to $10,000 per person in electronic I Bonds that are bought and held at the federal government website called TreasuryDirect.gov.
As a result, I Bond aficionados try to figure out the very best time to buy I Bonds during the year. They often game whether the fixed rate will go up or down when rates are announced May 1 or Nov. 1.
Typically, Enna notes, it’s savvy to buy I Bonds later during the month because if you buy I Bonds on April 20, for example, you’d get interest for all of April.
It’s often best to sell, by contrast, during the first few days of the month. If you redeem your I Bonds on April 20, for example, you’d lose all of the interest paid for April.
Going forward, Enna said he sees some possibility that the I Bond rate announced Nov. 1 could have a higher fixed rate than 0.9%, maybe something in a 1% or slightly higher range.
Hard to Know How Much Inflation Will Heat Up
Enna said watching the trend for inflation for the next six months will be interesting.
“We are in a new era of inflation. It’s hard to predict and hard to tell where we’re headed,” Enna said. He admits he’s always had a tough time predicting inflation even before now.
Inflation now, though, is clearly back on everyone’s radar.
“Inflation is high and will accelerate this year as the Iran war pushes up energy and other prices,” Mark Zandi, chief economist for Moody’s Analytics, told the Detroit Free Press, part of the USA TODAY Network.
Inflation as measured by the Personal Consumption Expenditures price index is currently near 3%, Zandi said, and it will be approaching 4% later this year. The Federal Reserve’s inflation target is 2%.
Zandi expects inflation to go up, thanks to higher energy prices, the ongoing impact of higher tariffs and the expansion of AI, which many expect will initially contribute to inflation.
When it comes to I Bonds, there’s still a short window to buy in April — say by April 28 or so — before the new rate kicks in.
An investor buying I Bonds in April will get a six-month annualized return of 4.03%, and then 4.26% for the next six months, Enna said. In that case, he said, you could be receiving an estimated 4.16% over 12 months.
Remember, though, the I Bond’s fixed rate could be reset on May 1, and we won’t know that until the Treasury makes its official announcement.
What to Consider If You’re Selling I Bonds
If you’re considering selling off some I Bonds, review the rates that you’re receiving on those particular bonds.
Paying attention to the fixed rate on I Bonds is something novice savers don’t realize is essential. Who, after all, would imagine that you’d need a very detailed chart to explain what fixed rate applies to what batch of I Bonds issued when. Yet such a chart exists online.
In an odd twist, I Bonds can carry all sorts of fixed rates that apply to the 30-year life of the bond, depending on when you bought it.
The first I Bonds that were issued in September 1998 continue to have a fixed rate of 3.4%. I Bonds bought from May 2000 through October 2000 carry a fixed rate of 3.6% — the highest fixed rate ever offered for I Bonds.
At the other extreme, we’ve got a long list of I Bonds issued in various years that have a 0% fixed rate.
The 0% fixed rate, for example, applies to a long stretch for I Bonds bought from May 2020 through October 2022. In that case, you’re only receiving the variable inflation rate for any given six-month stretch of time.
By contrast, I Bonds issued from November 2023 through October 2024 had a fixed rate of 1.3%.
Ideally, if you plan to cash in some I Bonds, you might consider selling off the batch with a 0% fixed rate and holding onto the ones that would continue to pay a fixed rate, no matter where inflation heads.
If you sell an I Bond before you’ve held it for five years, you are looking at a slight penalty.
If you cash in an I Bond in less than five years, you lose the last three months of interest. The TreasuryDirect.gov site gives an example: “If you cash in the bond after 18 months, you get the first 15 months of interest.”
After five years, Enna said, the interest penalty goes away and you can redeem at any time.
Cashing a savings bond will mean that most people must report all interest earned on the bond over time in the year that they cash the bond. For those cashing a great deal of bonds, it could be key to review your tax situation, perhaps talking to a tax professional first.
“You will pay taxes when you redeem,” Enna said.
Enna has personally been selling off his I Bonds that have a 0% fixed rate to reinvest in I Bonds that have a higher fixed rate.
“I don’t have any of those left, but I do have a few 0.1% and 0.2% versions I might roll over,” he said.
The threat of inflation remains real — especially when you realize that oil derivatives are found in everything from medical equipment to textiles and furniture. And ordering more online means nearly everything gets delivered — which could drive up all sorts of prices.
Inflation hurts on so many levels. But I Bonds could be seeing new life, as one way savers can get some protection from inflation.
Contact personal finance columnist Susan Tompor: [email protected]. Follow her on X @tompor.