No Result
View All Result
  • Login
Friday, September 18, 2026
FeeOnlyNews.com
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading
No Result
View All Result
FeeOnlyNews.com
No Result
View All Result
Home Personal Finance

What is Return-of-Premium Life Insurance and How Does It Work?

by FeeOnlyNews.com
2 months ago
in Personal Finance
Reading Time: 13 mins read
A A
0
What is Return-of-Premium Life Insurance and How Does It Work?
Share on FacebookShare on TwitterShare on LInkedIn


An insurance policy generally isn’t something you can return for your money back. But there’s one exception: return-of-premium (ROP) life insurance.

This type of coverage reimburses you for the money you paid in premiums if you don’t die during the term. Some insurers offer it as a stand-alone policy, though it’s commonly sold as a rider that can be added on to a life insurance policy. It can cost significantly more than a traditional life insurance policy.

What is return-of-premium life insurance?

Return-of-premium is a feature or rider added to an insurance policy that gives policyholders a refund of the premiums paid if they outlive their term.

When you buy a stand-alone ROP life insurance policy, you’ll choose a term length, such as 20 or 30 years. If you die during that time, your life insurance beneficiaries receive the death benefit. But if you don’t, you’ll get a refund of the premiums you paid, without interest.

How does return-of-premium life insurance work?

The money-back feature comes with a higher price tag. You can expect to pay three to five times as much for a return-of-premium policy compared with a standard term life insurance policy without ROP benefits.

Your insurer might also subtract the cost of administrative fees and similar charges. The money you get back isn’t taxable, as it’s simply a refund of the payments you made.

To compare, with regular term life insurance, you won’t receive any money if you’re still alive when the policy expires. However, you’d pay much less in premiums for the same amount of coverage.

Did you know…

ROP life insurance is usually a term life policy, but some policies can build cash value over time. Accumulating enough can take years, but eventually you might be able to borrow against your policy, withdraw the money or surrender the policy for cash if you no longer need coverage.

ROP life insurance pros and cons

Pros

Premiums are reimbursed if you outlive the policy.

Refunds aren’t taxed as income.

ROP policies can build cash value.

Cons

More expensive than regular term life insurance.

Won’t get any money back if your policy lapses.

Not usually available to applicants over 60.

Is return-of-premium life insurance worth it?

For most people, return-of-premium life insurance isn’t worth the extra cost. A standard term life insurance policy is sufficient and more affordable. Instead, put the money you don’t spend on a return-of-premium policy aside into a high-interest savings account, or invest it.

If you’re not comfortable with the idea of paying into a life insurance policy that may expire, consider the lifelong coverage offered by permanent life insurance policies like whole life.

The best stand-alone ROP insurance policies

If you do buy ROP insurance, you’ll need to choose whether you want a stand-alone policy or to add this feature to an existing life insurance policy.

This list focuses on return-of-premium policies that are sold separately. To narrow down the list, we looked at death benefit amounts, term lengths and state availability, as well as insurers’ financial strength and reputation among customers. All of the companies below scored at least 4.6 out of 5 stars.

NerdWallet rating

Term lengths available

State FarmBest for discounts

4.7 NerdWallet rating

NerdWallet’s ratings are determined by our editorial team. The scoring formula incorporates consumer experience, financial strength ratings and complaint data.

20 or 30 years.

Cincinnati Life InsuranceBest for transparency

4.6 NerdWallet rating

NerdWallet’s ratings are determined by our editorial team. The scoring formula incorporates consumer experience, financial strength ratings and complaint data.

20, 25 or 30 years.

Illinois MutualBest user-friendly policy

4.7 NerdWallet rating

NerdWallet’s ratings are determined by our editorial team. The scoring formula incorporates consumer experience, financial strength ratings and complaint data.

20 or 30 years or to age 65.

NerdWallet rates insurers at the company level, not the policy level. This means our star rating reflects the company as a whole, and not its ROP insurance policy specifically.

Best for discounts: State Farm

Open to applicants from 18 to 60 years old, State Farm’s return-of-premium life insurance policy offers coverage starting at $100,000 and capped at $250,000. Depending on your age, you can buy a policy lasting 20 or 30 years. If you’d like to convert your policy to permanent life insurance, you can do so up to age 75.

State Farm offers a multi-line discount for anyone who has auto insurance with the company and purchases a return-of-premium life insurance policy.

Best for transparency: The Cincinnati Life Insurance Company

Cincinnati Life’s Termsetter ROP policies start at $25,000 in coverage and can last 20, 25 or 30 years. The insurer doesn’t list a maximum coverage level. Instead, the amount of coverage you can buy depends on your age and your rating category. Cincinnati Life also offers a transparent application process with an underwriting professional on hand to answer questions.

With this insurer, some ROP applicants are eligible for accelerated underwriting, which skips the medical exam. The insurer is also lenient toward nonsmoking tobacco users when it comes to assigning a rating category.

Best user-friendly policy: Illinois Mutual

Illinois Mutual’s return-of-premium policy is straightforward. If you’re 18 to 60 years old, you can buy up to $500,000 in coverage, and add an accelerated death benefit rider to your policy. However, the policy isn’t available in Alaska, Hawaii, New York or the District of Columbia.

Although you can’t convert this term life policy to permanent life insurance, Illinois Mutual does allow you to renew a return-of-premium term policy annually up to age 95.

Companies that offer return-of-premium riders

These companies allow you to add a return-of-premium rider to specific policies. You can expect to pay higher premiums if you opt in to this coverage.

Company

Policies eligible for ROP rider

AAA

3.8 NerdWallet rating

NerdWallet’s ratings are determined by our editorial team. The scoring formula incorporates consumer experience, financial strength ratings and complaint data.

15-, 20- or 30-year term life insurance.

Country Financial

4.5 NerdWallet rating

NerdWallet’s ratings are determined by our editorial team. The scoring formula incorporates consumer experience, financial strength ratings and complaint data.

20- or 30-year term life insurance.

Foresters Financial

3.9 NerdWallet rating

NerdWallet’s ratings are determined by our editorial team. The scoring formula incorporates consumer experience, financial strength ratings and complaint data.

Accidental term life insurance.

Guardian

5.0 NerdWallet rating

NerdWallet’s ratings are determined by our editorial team. The scoring formula incorporates consumer experience, financial strength ratings and complaint data.

15, 20 and 25 policy years in universal life insurance.

John Hancock

4.6 NerdWallet rating

NerdWallet’s ratings are determined by our editorial team. The scoring formula incorporates consumer experience, financial strength ratings and complaint data.

25- and 30-year Simple Term with Vitality.

Pacific Life

4.8 NerdWallet rating

NerdWallet’s ratings are determined by our editorial team. The scoring formula incorporates consumer experience, financial strength ratings and complaint data.

15, 20, 25 and 35 policy years in guaranteed universal life insurance.

Find the right life insurance plan for you

Make sure you and your loved ones are covered – compare customized life insurance quotes from our partners.

Frequently Asked Questions

Is return-of-premium life insurance taxable?Is return-of-premium life insurance taxable?

Generally, no, and it’s for the same reason other types of life insurance aren’t considered taxable. The IRS considers life insurance proceeds, including death and ROP benefits, to be a return on the premiums you’ve paid and therefore not categorized as taxable income.

What’s the downside of return-of-premium life insurance?What’s the downside of return-of-premium life insurance?

ROP policies have the same disadvantage of many cash value life insurance offerings. Often, the additional money you’ll pay in premiums would earn more interest if you invested or saved the same amount in a high-yield savings or money market account instead.
What type of life insurance offers a return of your premiums?What type of life insurance offers a return of your premiums?

Most return-of-premium coverage is an add-on to term life insurance. In some cases, you may find return-of-premium riders on universal life insurance policies.

For instance, Guardian, one of our best life insurance companies of 2026, has a return-of-premium rider available for universal life insurance that offers exit points where you can surrender your policy and get a portion of your premiums back.

Methodology

How we rate the best life insurance companies

✅ 445 life insurers reviewed

📝 210 policies assessed

🔢 1,515 data points analyzed

📊 Star rating categories

When NerdWallet evaluates life insurance companies, our editorial team considers the insurer’s strengths and weaknesses, as well as the things that matter most to customers buying a long-term financial product. We then weigh these factors carefully:

💰 Financial strength (35%). We use AM Best ratings to confirm an insurer’s financial stability and ability to pay claims far into the future. The top life insurance companies have an exceptional financial strength rating of A+ or A++ (Superior).

🗣️ Consumer complaints (35%). Our top-rated life insurance companies have fewer than the expected number of complaints to state regulators over a three-year period, according to the National Association of Insurance Commissioners — so you can expect a smoother customer experience.

☎️ Consumer experience (20%). Insurers who allow consumers to contact them by email, phone and live chat earn the highest scores. The same goes for insurers who support online quotes, beneficiary changes and claims.

👀 Transparency (10%). Our methodology gives higher scores to transparent insurers who clearly display information about their policy options, coverage amounts and term lengths (if applicable) on their site.

⭐ What our star ratings mean

Companies with 5 stars are exceptional, with strong financials, diverse policy lineups and great reputations for customer service.

Companies with 4.5 stars are excellent, with solid financials and policy offerings, and good customer service track records.

Companies with 4.0 stars are good, and potentially great for people looking for niche coverage options.

Companies with 3.5 stars or fewer could do better in certain categories, like financial strength and customer complaints.

Addas a preferred source on Google

About the author

Kaz Weida

Kaz Weida is a writer and content strategist specializing in insurance. Before joining NerdWallet, she was a freelance journalist for over a decade with a focus on personal finance, politics and technology. Her work has appeared in CNET, Popular Mechanics, Yahoo Finance, Consumer Affairs, DAME Magazine and The Penny Hoarder. As a former teacher, Kaz enjoys educating consumers about complicated topics like insurance to encourage healthier financial decisions. She lives in northern Vermont.
Source link

Tags: InsuranceLifeReturnofPremiumwork
ShareTweetShare
Previous Post

Sam’s Links: July Edition – Econlib

Next Post

Links 7/31/2026 | naked capitalism

Related Posts

Hanes Kids’ Sock 20-Packs and Underwear 12-Packs only .50 each, plus more!

Hanes Kids’ Sock 20-Packs and Underwear 12-Packs only $7.50 each, plus more!

by FeeOnlyNews.com
August 7, 2026
0

Published: by Sarah on August 7, 2026  |  This post may contain affiliate links. Read my disclosure policy here. Score great prices...

Comforter 8-Piece Sets with Sheets as low as .93 at Macy’s! {All Sizes}

Comforter 8-Piece Sets with Sheets as low as $29.93 at Macy’s! {All Sizes}

by FeeOnlyNews.com
August 7, 2026
0

Home » Deals » Comforter 8-Piece Sets with Sheets as low as $29.93 at Macy’s! {All Sizes} Published: by Sarah...

Mortgage Rates Today, Friday, August 7: Higher for Now

Mortgage Rates Today, Friday, August 7: Higher for Now

by FeeOnlyNews.com
August 7, 2026
0

Mortgage rates are a little higher this morning, but are likely to soften on the heels of a lackluster jobs...

What You Can Learn From the Nerds’ Home Improvement Projects

What You Can Learn From the Nerds’ Home Improvement Projects

by FeeOnlyNews.com
August 6, 2026
0

Do you have a home improvement project on your to-do list? You might have a deck to build or a...

FOUR Big Tide Laundry Detergents for only .72 each, shipped (Plus, Tide Pods deal)!

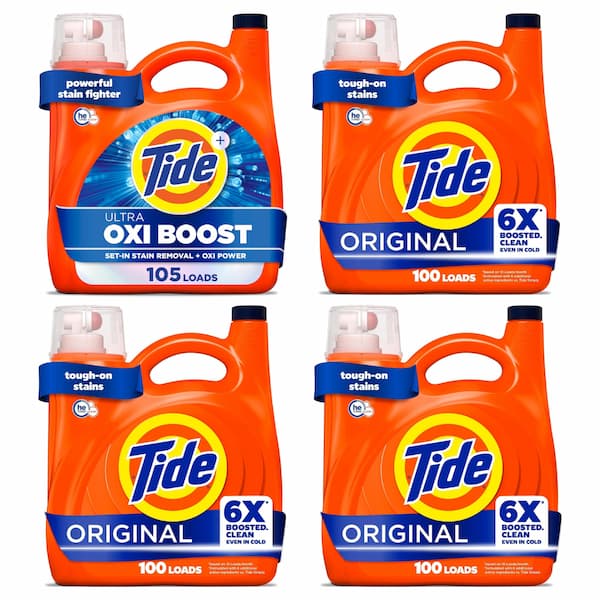
FOUR Big Tide Laundry Detergents for only $10.72 each, shipped (Plus, Tide Pods deal)!

by FeeOnlyNews.com
August 6, 2026
0

Home » Deals » FOUR Big Tide Laundry Detergents for only $10.72 each, shipped (Plus, Tide Pods deal)! Published: by...

Mortgage Rates Flatten, but They’re Already Higher Than July’s Average

Mortgage Rates Flatten, but They’re Already Higher Than July’s Average

by FeeOnlyNews.com
August 6, 2026
0

In the first week of August, the average 30-year mortgage rate stayed mostly flat at 6.63% APR. This is three...

Next Post
Links 7/31/2026 | naked capitalism

Links 7/31/2026 | naked capitalism

How to Analyze a Rental Property Step-by-Step (15 Years of Experience)

How to Analyze a Rental Property Step-by-Step (15 Years of Experience)

  • Trending
  • Comments
  • Latest
Bitcoin and ethereum prices today, Friday, August 7, 2026: Crypto prices moving higher following July jobs report

Bitcoin and ethereum prices today, Friday, August 7, 2026: Crypto prices moving higher following July jobs report

August 7, 2026
MEXC Lists Ondo Yield Asset As Tokenized Treasury Demand Grows

MEXC Lists Ondo Yield Asset As Tokenized Treasury Demand Grows

July 3, 2026
Delek Logistics Partners Reports alt=

Delek Logistics Partners Reports $0.54 EPS for Q2 FY26

August 5, 2026
Onkure Therapeutics Releases Q2 2026 Financial Results

Onkure Therapeutics Releases Q2 2026 Financial Results

August 4, 2026
Thryv outlines M run-rate savings while revising 2026 SaaS adjusted EBITDA to M-M (NASDAQ:THRY)

Thryv outlines $60M run-rate savings while revising 2026 SaaS adjusted EBITDA to $42M-$44M (NASDAQ:THRY)

August 4, 2026
My Thoughts on Going All In

My Thoughts on Going All In

August 4, 2026
Advanced Micro Devices (AMD) Price Prediction: How Much a ,000 Investment Could Be Worth by 2031

Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031

0
Cities holding up to 3 million people found under Amazon rain forest

Cities holding up to 3 million people found under Amazon rain forest

0
Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

0
Bybit Uses Tokenised Equities as Underlyings for Structured Yield

Bybit Uses Tokenised Equities as Underlyings for Structured Yield

0
Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

0
Vaxart outlines Phase IIb COVID-19 top line data in first half of 2027 backed by BARDA funding (OTCMKTS:VXRT)

Vaxart outlines Phase IIb COVID-19 top line data in first half of 2027 backed by BARDA funding (OTCMKTS:VXRT)

0
Advanced Micro Devices (AMD) Price Prediction: How Much a ,000 Investment Could Be Worth by 2031

Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031

August 8, 2026
Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

August 8, 2026
Vanguard Chief Economist: AI and jobs, still in an ATM phase

Vanguard Chief Economist: AI and jobs, still in an ATM phase

August 8, 2026
Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

August 8, 2026
Democrats’ Affordability Message Misses a Key Expense—Student Debt

Democrats’ Affordability Message Misses a Key Expense—Student Debt

August 8, 2026
Banks or NBFCs? DSP’s Preethi R S explains where she sees the best opportunities

Banks or NBFCs? DSP’s Preethi R S explains where she sees the best opportunities

August 8, 2026
FeeOnlyNews.com

Get the latest news and follow the coverage of Business & Financial News, Stock Market Updates, Analysis, and more from the trusted sources.

CATEGORIES

  • Business
  • Cryptocurrency
  • Economy
  • Financial Planning
  • Investing
  • Market Analysis
  • Markets
  • Money
  • Personal Finance
  • Startups
  • Stock Market
  • Trading

LATEST UPDATES

  • Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031
  • Republican Party Displacement | Mises Institute
  • Vanguard Chief Economist: AI and jobs, still in an ATM phase
  • Our Great Privacy Policy
  • Terms of Use, Legal Notices & Disclaimers
  • About Us
  • Contact Us

Copyright © 2022-2024 All Rights Reserved
See articles for original source and related links to external sites.

Welcome Back!

Sign In with Facebook
Sign In with Google
Sign In with Linked In
OR

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In
No Result
View All Result
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading

Copyright © 2022-2024 All Rights Reserved
See articles for original source and related links to external sites.