No Result
View All Result
  • Login
Sunday, September 20, 2026
FeeOnlyNews.com
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading
No Result
View All Result
FeeOnlyNews.com
No Result
View All Result
Home Money

Are women getting the right advice about RESPs?

by FeeOnlyNews.com
5 months ago
in Money
Reading Time: 4 mins read
A A
0
Are women getting the right advice about RESPs?
Share on FacebookShare on TwitterShare on LInkedIn


Knowing firsthand what an emotional and financial burden student debt can be, I was determined to give my kids a better post-secondary experience and a solid foundation for their adult lives. 

A little over a month after our daughter’s birth, my husband and I headed to our bank with the baby nestled against my body in a fabric wrap. We opened the RESP together, setting up regular contributions from our joint bank account, and felt good about the investment we were making in our child’s future. 

Years later, we have two teenagers and a family RESP with a healthy balance, but I have regrets—and zero access to those funds. Here’s why, plus everything you should know before setting up an RESP for your child.

RESPs 101

If you’re thinking about opening an RESP for your child (or children), there are a few important things to know. The terminology is unique and can be confusing, so let’s break it down:

Subscriber: The person (or people) who open the RESP, make financial contributions and determine the type of investments within the account, as well as the level of risk tolerance. The subscriber(s) are commonly the child’s parent(s), but other adult family members can also open RESPs.

Primary caregiver: The person who receives the Canada Child Benefit (CCB) and is considered primarily responsible for the child’s care and education. This is typically the mother and defaults as such, though you can file paperwork to amend this.

Beneficiary: The child (or children) who will eventually receive funds from the RESP if all legal requirements, such as proof of enrollment in a qualifying post-secondary institution, are met.

Promoter: The financial institution involved (your bank, a credit union, or an investment firm).

If this seems complicated, it’s because it is. “They use all this jargon,” says Liz Schieck, an educator and certified financial planner (CFP) with The New School of Finance in Toronto. 

Schieck notes that in order to open an RESP for a child, you must have the child’s social insurance number (SIN). If multiple RESPs are opened for the same child, the primary caregiver designation remains the same across all accounts. This is because the Canada Education Savings Grant (CESG) is connected to the primary caregiver rather than the subscriber, and there is a lifetime limit on grant contributions per child that does not grow exponentially when multiple accounts are opened.

Translation: If you open an RESP for your child and so does a grandparent and a generous uncle, the maximum government grant amount stays the same rather than tripling.

The risks of misinformation (or bad advice)

When my husband and I set up our kids’ RESP, we were blissfully unaware of how many options we had. After politely declining to work with an RESP firm that contacted us days after our daughter’s birth, we made an appointment with our bank, a major financial institution that already held our savings and RRSPs. 

Article Continues Below Advertisement

Outstream Volume Icon

Skip Ad

X

We asked questions during the appointment, heeded the advice we were given, and set up the account with my husband listed as a subscriber and me listed as the primary caregiver. It wasn’t until later that I realized how different those roles are and what I’d agreed to as a sleep-deprived new mom. 

During the appointment with our bank, we were told that one parent would take on the role of subscriber (a term that was new to us) and the other would be listed as the primary caregiver. When we asked if both of us could be listed as subscribers, we were told no. The primary caregiver role defaulted to me—the parent receiving the Canada Child Benefit due to its maternal presumption policy—and my husband was the higher income earner at the time, so it seemed logical that he would fill the role of subscriber. Because the money was being invested for our children and my name was on the account as their primary caregiver, I still felt like we held the RESP jointly—an assumption that seems naive in retrospect.

As the primary caregiver on my children’s RESP, I have no control of or access to the funds in the account. I can’t check the balance of our kids’ RESP or make contributions. I have no say over how the money is invested, when it’s withdrawn, and how it will eventually be distributed. 

Fortunately, I’m still happily married to my husband—but if that were ever to change, he’d have control of over $100k in invested funds that we built together.

How do RESPs work?

Learn what they are and how to fund them

“When you set up an RESP with your partner, you aren’t necessarily examining the difference in power between the two roles,” Schieck says, who has seen scenarios like mine before. “But both partners should have the ability to make decisions around that account, including the money going in and the types of investments.” 

Schieck explains that while the Government of Canada asserts that an RESP can be jointly held by two subscribers, not all financial institutions offer this setup. When I reached out to my financial institution for clarification earlier this month, they responded that you can open a sole-subscriber RESP at any of their bank branches across Canada, but you can only open joint-subscriber RESPs via their direct investing and securities advisors. The latter option wasn’t presented to me at the branch level, nor was it discussed when I asked the bank questions about the RESP last year.

This is a problem, Schieck says. “When you’re choosing a financial institution for your kids’ RESP, I’d recommend asking if they allow joint subscribers before you open the account.”

How to protect yourself while investing in your kids’ future

There is no official explanation for why some institutions only offer sole-subscriber RESPs, or only provide jointly-held RESPs through specific channels, but we can make certain assumptions. 


Source link

Tags: AdviceRESPswomen
ShareTweetShare
Previous Post

Top 5 – Savings Plans with High Returns in 2026

Next Post

Maduro Raid Commando Pleads Not Guilty After $400K Polymarket Bet on His Own Mission

Related Posts

6 Part-Time Jobs Retirees Can Explore Before the Holiday Hiring Rush

6 Part-Time Jobs Retirees Can Explore Before the Holiday Hiring Rush

by FeeOnlyNews.com
August 7, 2026
0

The weeks before the holiday hiring rush can be a surprisingly good time for retirees to decide whether a little...

Medicare Deadlines New Retirees Should Put on the Calendar Before Leaving Work

Medicare Deadlines New Retirees Should Put on the Calendar Before Leaving Work

by FeeOnlyNews.com
August 7, 2026
0

A 65-year-old retiring in November may have a completely different Medicare timeline from a 68-year-old leaving an employer health plan...

8 Side Effects of Aging That No One Prepares You For

8 Side Effects of Aging That No One Prepares You For

by FeeOnlyNews.com
August 7, 2026
0

Aging is often portrayed as a graceful journey filled with wisdom, leisure, and newfound freedom. While those aspects can certainly...

Stock news for investors: Quarterly earnings from Telus, Shopify, BCE, and more

Stock news for investors: Quarterly earnings from Telus, Shopify, BCE, and more

by FeeOnlyNews.com
August 6, 2026
0

The company reported a loss attributable to common shareholders of $1.8 billion or $1.17 per share for the quarter ended...

The world’s largest corporate holder of Bitcoin has been selling—should you be concerned?

The world’s largest corporate holder of Bitcoin has been selling—should you be concerned?

by FeeOnlyNews.com
August 6, 2026
0

While selling BTC is not alarming in itself, it seems to go against Executive Chairman Micheal Saylor’s public image as...

7 Warning Signs an Older Adult May Be Under Financial Pressure

7 Warning Signs an Older Adult May Be Under Financial Pressure

by FeeOnlyNews.com
August 6, 2026
0

It often starts with what seems like a harmless favor. A relative offers to help pay bills online. A new...

Next Post
Maduro Raid Commando Pleads Not Guilty After 0K Polymarket Bet on His Own Mission

Maduro Raid Commando Pleads Not Guilty After $400K Polymarket Bet on His Own Mission

US-Led Sanctions: The End of a Regime

US-Led Sanctions: The End of a Regime

  • Trending
  • Comments
  • Latest
Bitcoin and ethereum prices today, Friday, August 7, 2026: Crypto prices moving higher following July jobs report

Bitcoin and ethereum prices today, Friday, August 7, 2026: Crypto prices moving higher following July jobs report

August 7, 2026
MEXC Lists Ondo Yield Asset As Tokenized Treasury Demand Grows

MEXC Lists Ondo Yield Asset As Tokenized Treasury Demand Grows

July 3, 2026
Delek Logistics Partners Reports alt=

Delek Logistics Partners Reports $0.54 EPS for Q2 FY26

August 5, 2026
Onkure Therapeutics Releases Q2 2026 Financial Results

Onkure Therapeutics Releases Q2 2026 Financial Results

August 4, 2026
Thryv outlines M run-rate savings while revising 2026 SaaS adjusted EBITDA to M-M (NASDAQ:THRY)

Thryv outlines $60M run-rate savings while revising 2026 SaaS adjusted EBITDA to $42M-$44M (NASDAQ:THRY)

August 4, 2026
My Thoughts on Going All In

My Thoughts on Going All In

August 4, 2026
Advanced Micro Devices (AMD) Price Prediction: How Much a ,000 Investment Could Be Worth by 2031

Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031

0
Cities holding up to 3 million people found under Amazon rain forest

Cities holding up to 3 million people found under Amazon rain forest

0
Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

0
Bybit Uses Tokenised Equities as Underlyings for Structured Yield

Bybit Uses Tokenised Equities as Underlyings for Structured Yield

0
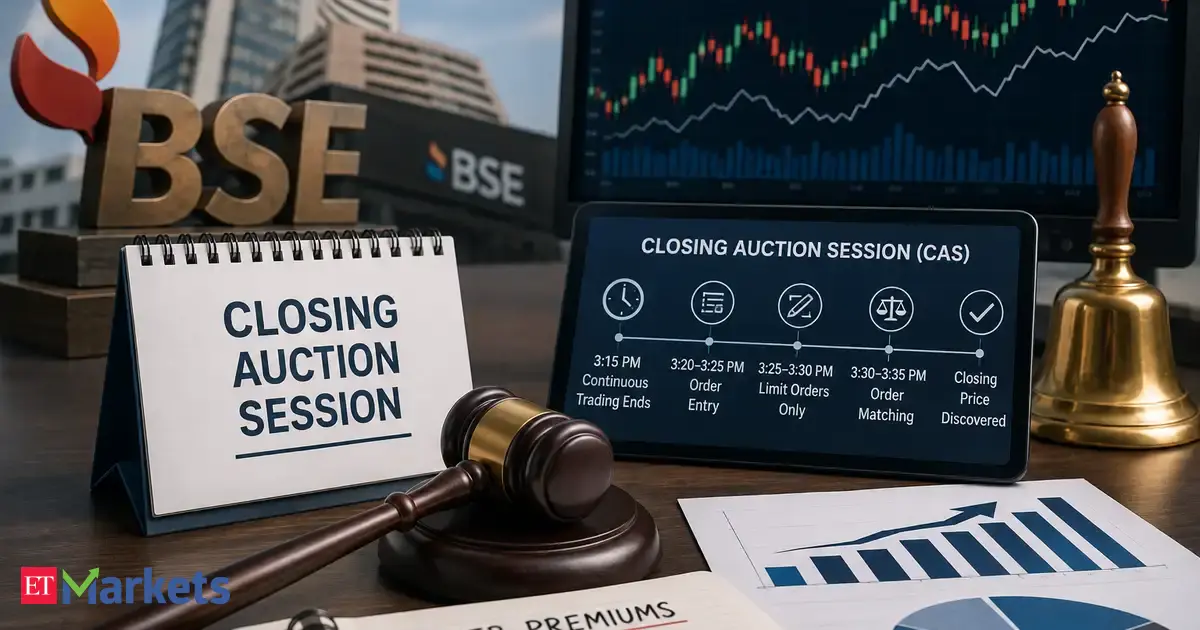
Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

0
Vaxart outlines Phase IIb COVID-19 top line data in first half of 2027 backed by BARDA funding (OTCMKTS:VXRT)

Vaxart outlines Phase IIb COVID-19 top line data in first half of 2027 backed by BARDA funding (OTCMKTS:VXRT)

0
Advanced Micro Devices (AMD) Price Prediction: How Much a ,000 Investment Could Be Worth by 2031

Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031

August 8, 2026
Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

August 8, 2026
Vanguard Chief Economist: AI and jobs, still in an ATM phase

Vanguard Chief Economist: AI and jobs, still in an ATM phase

August 8, 2026
Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

August 8, 2026
Democrats’ Affordability Message Misses a Key Expense—Student Debt

Democrats’ Affordability Message Misses a Key Expense—Student Debt

August 8, 2026
Banks or NBFCs? DSP’s Preethi R S explains where she sees the best opportunities

Banks or NBFCs? DSP’s Preethi R S explains where she sees the best opportunities

August 8, 2026
FeeOnlyNews.com

Get the latest news and follow the coverage of Business & Financial News, Stock Market Updates, Analysis, and more from the trusted sources.

CATEGORIES

  • Business
  • Cryptocurrency
  • Economy
  • Financial Planning
  • Investing
  • Market Analysis
  • Markets
  • Money
  • Personal Finance
  • Startups
  • Stock Market
  • Trading

LATEST UPDATES

  • Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031
  • Republican Party Displacement | Mises Institute
  • Vanguard Chief Economist: AI and jobs, still in an ATM phase
  • Our Great Privacy Policy
  • Terms of Use, Legal Notices & Disclaimers
  • About Us
  • Contact Us

Copyright © 2022-2024 All Rights Reserved
See articles for original source and related links to external sites.

Welcome Back!

Sign In with Facebook
Sign In with Google
Sign In with Linked In
OR

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In
No Result
View All Result
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading

Copyright © 2022-2024 All Rights Reserved
See articles for original source and related links to external sites.