No Result
View All Result
  • Login
Monday, September 21, 2026
FeeOnlyNews.com
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading
No Result
View All Result
FeeOnlyNews.com
No Result
View All Result
Home Economy

Bond Market Sell Off: Welcome to the “Titanic Effect”

by FeeOnlyNews.com
3 months ago
in Economy
Reading Time: 4 mins read
A A
0
Bond Market Sell Off: Welcome to the “Titanic Effect”
Share on FacebookShare on TwitterShare on LInkedIn


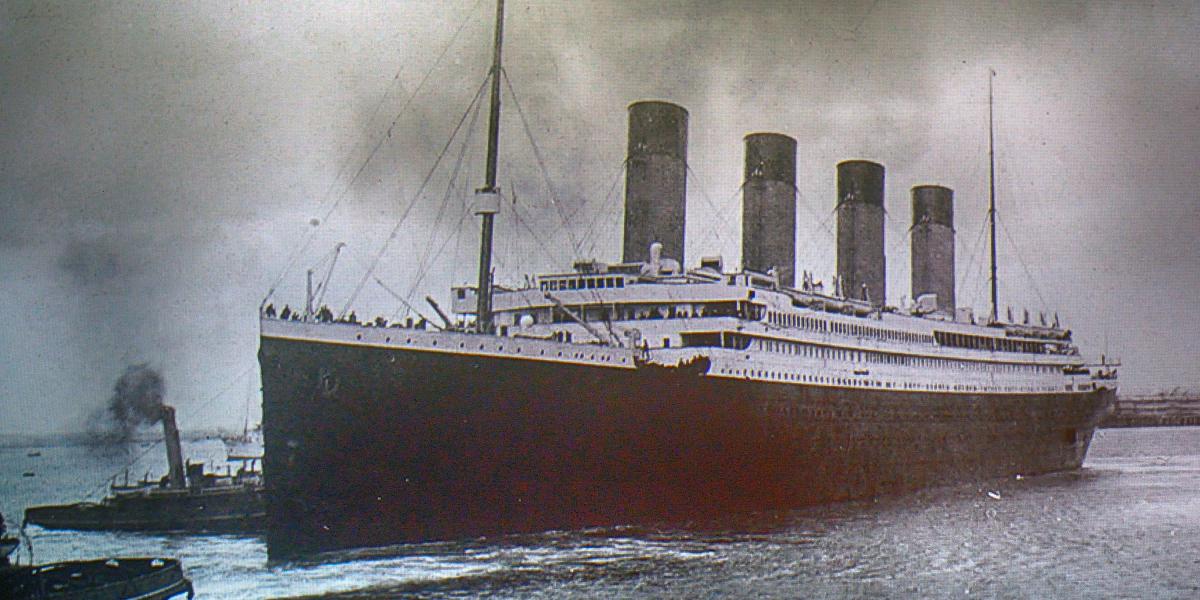
On April 14, 1912, at 11:40 pm, the Titanic—the legendary passenger ship regarded as unsinkable—tore open its hull on an iceberg during its maiden voyage from Southampton to New York. The watertight compartments filled with water, and—just 2 hours and 40 minutes later—the ship sank in the icy waters of the North Atlantic. Approximately 1,517 people lost their lives—not least because the Titanic did not carry enough lifeboats and the crew failed to summon help by radio in time.

To stay with the metaphor: Just as the iceberg collision ultimately led to the Titanic’s demise, a continued rise in interest rates can plunge the global financial and economic system into severe distress and, in the extreme case, trigger a fatal collapse, the going under, of the world’s financial and economic system. Let us call this the “Titanic Effect.”

Since 2020, interest rates have been climbing more or less steadily. The yield on 10-year US Treasuries, for example, has risen from 0.65 percent to currently around 4.5 percent. Yet the interest rate increase now appears to have taken on a momentum of its own. It has become more than just a “normalization” that merely lifts rates from extremely low levels back to historically more normal heights.

On the credit markets, doubts about the credit quality of many debtors are spreading, especially regarding government borrowers. This is hardly surprising given the enormous mountains of debt that governments—often enthusiastically encouraged by their voters—have piled up over recent decades. Living on credit was relatively easy because interest rates kept falling.

This long-term decline in interest rates was primarily the work of central banks under their fiat money regimes. In close cooperation with commercial banks, they continuously expand the money supply through bank credit creation. This allows not only consumers and producers, but especially governments, to finance their spending on a massive scale with credit at low cost.

Rising interest rates are now putting an end to this. They are causing interest payments to explode—and that is a huge problem. After all, governments typically do not repay their maturing debts on a net basis. Instead, they replace maturing debt with new debt—a strategy that works well as long as interest rates keep falling.

In an over-indebted fiat money system, however, rising interest rates are, to continue the metaphor, like a gash in the ship’s hull through which water floods in: The interest burden on outstanding debt keeps rising because maturing loans that are not repaid must be refinanced with new loans carrying higher interest rates. On top of that, new debt is constantly being added.

Take the United States of America as an example. In mid-2020, the US government’s annual interest bill stood at $508 billion, and, by the first quarter of 2026, it had climbed to $1,219 billion. Back then, total debt was $26.4 trillion; today it stands at around $39 trillion. The average refinancing rate is currently 3.1 percent. If it were to rise permanently to 4.5 percent, Americans would have to pay nearly $1.8 trillion in interest every year.

The interest burden already amounts to 3.8 percent of GDP—significantly higher than average economic growth. At a 4.5 percent interest rate, it would rise to a staggering 5.8 percent. The situation looks similar or even worse in many other economies—think of Japan, France, Italy, the United Kingdom, or Germany.

You don’t need to be a rocket scientist to realize that this cannot be sustained indefinitely. It is like water pouring into the hull: if the inflow is not stopped, the ship will eventually sink—not immediately, but gradually and inexorably. So what should investors expect?

Finding an answer to this question is probably not as difficult as it might first seem, because developments in the credit market are, to a large extent, pre-determined. Market interest rates have long been politicized by central banks. And there is no doubt that central bankers can fully control market interest rates at any time if it is politically desired.

So far, however, central bankers have not fully used their power over interest rates. They have allowed capital market rates to climb higher in recent years, presumably viewing this as a kind of “interest rate normalization.”

Yet, as already noted, further rising interest rates will steer the fiat money system into extremely dangerous waters. They could even cause the global debt pyramid to collapse. Rising rates worsen the debt-servicing capacity of many borrowers—which, in turn, drives refinancing costs even higher. A vicious downward spiral begins (that is, more and more water floods into the hull).

Not only the economy, but especially asset markets come under increasing pressure when interest rates continue to rise or remain high. Many investments no longer make economic sense, companies go bankrupt, and jobs are lost. Rising interest rates also push down the prices of stocks, real estate, land, and commodities.

It is therefore highly likely that central bankers will intervene in the credit markets once interest rates become too high and politically unsustainable. For example, by buying government bonds and paying for them with newly-created money. The consequence will be an expansion of the money supply and, sooner or later, rising goods prices across the board.

What does it mean for the investor? Here are four important conclusions:

The investor faces the challenge of protecting his capital from currency debasement. Inflation (broad-based increases in goods prices) remains the greater risk for him going forward than deflation (a continued broad-based decline in goods prices).

The investor must achieve a positive real interest rate after taxes—and this is crucial to understand. Only then can he escape inflation; a positive real return after taxes is also the only way for the investor to actually grow his capital.

Positive real returns after taxes can no longer be achieved with savings accounts, money market funds, or government bonds. What remains is, for example, the stock market. However, it is very important to note: The investor must ensure he does not buy stocks at inflated prices—otherwise he risks failing to achieve the necessary real return (after taxes).

The investor should (continue to) hold a portion of his portfolio in gold and silver. Even though precious metal prices are currently undergoing a correction, there are good reasons to expect the long-term upward trend in gold and precious metals to resume soon. Gold and silver serve as insurance with upside potential for the investment portfolio—they are, so to speak, the lifeboats that are indispensable for investors in a fiat money regime now experiencing a “Titanic Effect” (where it is unclear how much longer the ship’s compartments will continue to fill with water).


Source link

Tags: bondEffectmarketSellTitanic
ShareTweetShare
Previous Post

InCred Money gets Sebi in-principle nod for mutual fund licence, plans launch in 6-9 months

Next Post

Ethos Life Insurance Review – No-Exam Term Life Built for Modern Families

Related Posts

Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

by FeeOnlyNews.com
August 8, 2026
0

Mark Thornton returns to Rothbard’s idea of major party realignment, arguing that ideology—not interest-group politics alone—drives long-term political change. He...

Democrats’ Affordability Message Misses a Key Expense—Student Debt

Democrats’ Affordability Message Misses a Key Expense—Student Debt

by FeeOnlyNews.com
August 8, 2026
0

Yves here. Although this article on student debt traps does not make these assumptions, many articles I see about student...

The Unwinnable Iran War | Armstrong Economics

The Unwinnable Iran War | Armstrong Economics

by FeeOnlyNews.com
August 8, 2026
0

I have reported that Trump was mislead into this unwinnable war with Iran, which has been planning for it since...

Here are three key takeaways from the disappointing July jobs report

Here are three key takeaways from the disappointing July jobs report

by FeeOnlyNews.com
August 7, 2026
0

Job seekers speak with employer representatives and browse information tables as they attend an Inspire Together job and resource fair...

Coffee Break: Gene Editing Gone Wrong, Plants that Eat Animals, and a Neanderthal Gene that Makes a Difference

Coffee Break: Gene Editing Gone Wrong, Plants that Eat Animals, and a Neanderthal Gene that Makes a Difference

by FeeOnlyNews.com
August 7, 2026
0

Part the First: If You Stretch Biomedical Science Too Far It Breaks, Every Time.  Gene editing using CRISPR technology has...

Netanyahu’s Scorched Earth Tactics | Armstrong Economics

Netanyahu’s Scorched Earth Tactics | Armstrong Economics

by FeeOnlyNews.com
August 7, 2026
0

According to formal complaints lodged by Lebanon with the United Nations, Israel did spray a toxic herbicide over agricultural land...

Next Post
Ethos Life Insurance Review – No-Exam Term Life Built for Modern Families

Ethos Life Insurance Review – No-Exam Term Life Built for Modern Families

8 Best Term Life Insurance Companies

8 Best Term Life Insurance Companies

  • Trending
  • Comments
  • Latest
MEXC Lists Ondo Yield Asset As Tokenized Treasury Demand Grows

MEXC Lists Ondo Yield Asset As Tokenized Treasury Demand Grows

July 3, 2026
Delek Logistics Partners Reports alt=

Delek Logistics Partners Reports $0.54 EPS for Q2 FY26

August 5, 2026
Ship and Debit Automation: A 2026 Guide to Margin Protection

Ship and Debit Automation: A 2026 Guide to Margin Protection

July 30, 2026
China threatens retaliation against U.S. humanoid robot ban, says it ‘severely damages’ relations

China threatens retaliation against U.S. humanoid robot ban, says it ‘severely damages’ relations

July 29, 2026
The AI Race With China Is a Lie Told by Big Tech to Justify the Data Center Invasion

The AI Race With China Is a Lie Told by Big Tech to Justify the Data Center Invasion

July 27, 2026
Here’s When Amazon’s ROI Will Pull Ahead of Microsoft’s in the AI Cloud Spend War

Here’s When Amazon’s ROI Will Pull Ahead of Microsoft’s in the AI Cloud Spend War

July 20, 2026
Advanced Micro Devices (AMD) Price Prediction: How Much a ,000 Investment Could Be Worth by 2031

Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031

0
Cities holding up to 3 million people found under Amazon rain forest

Cities holding up to 3 million people found under Amazon rain forest

0
Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

0
Bybit Uses Tokenised Equities as Underlyings for Structured Yield

Bybit Uses Tokenised Equities as Underlyings for Structured Yield

0
Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

0
Vaxart outlines Phase IIb COVID-19 top line data in first half of 2027 backed by BARDA funding (OTCMKTS:VXRT)

Vaxart outlines Phase IIb COVID-19 top line data in first half of 2027 backed by BARDA funding (OTCMKTS:VXRT)

0
Advanced Micro Devices (AMD) Price Prediction: How Much a ,000 Investment Could Be Worth by 2031

Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031

August 8, 2026
Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

August 8, 2026
Vanguard Chief Economist: AI and jobs, still in an ATM phase

Vanguard Chief Economist: AI and jobs, still in an ATM phase

August 8, 2026
Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

August 8, 2026
Democrats’ Affordability Message Misses a Key Expense—Student Debt

Democrats’ Affordability Message Misses a Key Expense—Student Debt

August 8, 2026
Banks or NBFCs? DSP’s Preethi R S explains where she sees the best opportunities

Banks or NBFCs? DSP’s Preethi R S explains where she sees the best opportunities

August 8, 2026
FeeOnlyNews.com

Get the latest news and follow the coverage of Business & Financial News, Stock Market Updates, Analysis, and more from the trusted sources.

CATEGORIES

  • Business
  • Cryptocurrency
  • Economy
  • Financial Planning
  • Investing
  • Market Analysis
  • Markets
  • Money
  • Personal Finance
  • Startups
  • Stock Market
  • Trading

LATEST UPDATES

  • Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031
  • Republican Party Displacement | Mises Institute
  • Vanguard Chief Economist: AI and jobs, still in an ATM phase
  • Our Great Privacy Policy
  • Terms of Use, Legal Notices & Disclaimers
  • About Us
  • Contact Us

Copyright © 2022-2024 All Rights Reserved
See articles for original source and related links to external sites.

Welcome Back!

Sign In with Facebook
Sign In with Google
Sign In with Linked In
OR

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In
No Result
View All Result
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading

Copyright © 2022-2024 All Rights Reserved
See articles for original source and related links to external sites.