Ten days remain before the statutory deadline for federal agencies to publish the implementing rules under the GENIUS Act. As of this week, the rulebook is still missing, leaving stablecoin issuers to prepare against proposed texts rather than binding regulations.
Seven federal agencies – the OCC, FDIC, Federal Reserve, NCUA, Treasury, FinCEN and OFAC – are required to complete the stablecoin rulemaking by July 18, one year after the law was signed.
Between December 2025 and June 2026, they released proposals covering capital, reserves, liquidity, redemption, financial crime compliance and credit union-affiliated issuers.
The drafts do not settle the details, but they show the direction of the first federal stablecoin regime: higher capital and liquidity standards, tighter reserve rules, and bank-style compliance obligations for issuers.
The Rulebook is Still in Draft, but the Outline Is Already Clear
The Office of the Comptroller of the Currency (OCC) published the most detailed proposal in February, setting out how federally supervised stablecoin issuers would be licensed, examined and required to manage reserves and redemptions.
In the following months, other agencies filled in separate parts of the framework: bank-affiliated issuers, state regime certification, anti-money laundering controls and sanctions compliance. Comments on the main proposals closed by June 9.
The National Credit Union Administration (NCUA), which oversees credit unions, came later than the other agencies: its proposal for credit union-affiliated stablecoin issuers was published in May, and the comment period closes on July 17, one day before the deadline.
The Federal Reserve has not published a standalone proposal for stablecoin issuers under its supervision, joining only the interagency customer identification proposal released in June. That leaves subsidiaries of state member banks without the same agency-specific roadmap that OCC- and FDIC-supervised issuers already have.
That creates an unusual situation: parts of the statutory framework could become effective before the Federal Reserve finalises its customer-identification rules.
Agencies miss statutory rulemaking deadlines regularly and face no formal penalty for doing so. The practical consequence is timing, covered below.
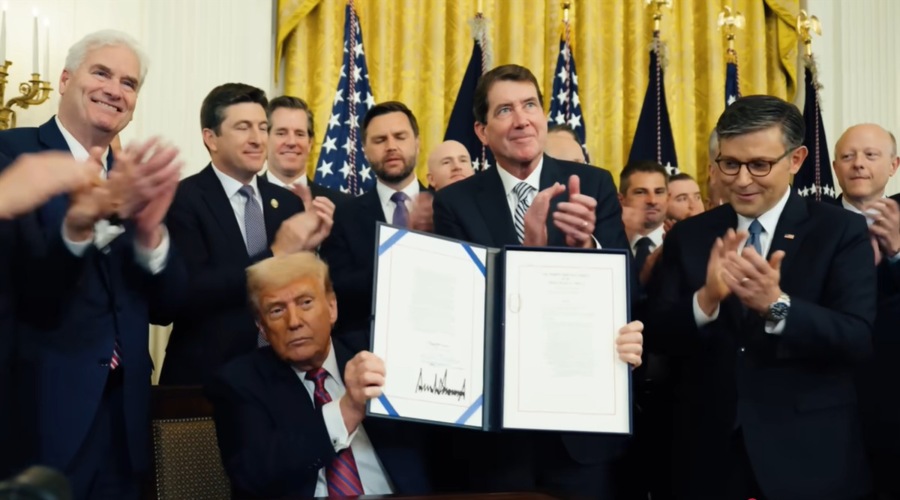
Trump Signs GENIUS Act Into Law, Setting Stage for Wider Crypto Oversight
Trump’s Genius and Crypto Acts Stall, But He’ll Be Back
What Issuers Will Have to Comply With
The core of the regime sits in the statute itself and will not move. Every permitted issuer must hold 1:1 reserves in eligible assets. Rehypothecation of those reserves is prohibited for most purposes.
Issuers must also publish monthly reserve reports covering reserve composition, outstanding supply and tenor. Those reports must be certified by the CEO and CFO and accompanied by a third-party attestation from a registered accounting firm.
The statute also fixes the financial crime baseline: issuers become financial institutions under the Bank Secrecy Act, the same legal status as a bank.
The FinCEN and OFAC proposal spells out what that requires in practice – board-approved AML programmes, suspicious activity reporting, sanctions screening and the ability to block or freeze tokens when required by law. FinCEN estimates the rules would initially apply to around 50 issuers.
The proposed rules add the prudential detail. The OCC has proposed a $5 million minimum capital floor for new federal issuers, with additional risk-based requirements for larger or more complex firms.
The proposal also narrows what can count as a reserve asset. Eligible assets would include cash, balances at Federal Reserve Banks, insured demand deposits, Treasury bills, and overnight Treasury repos.
Liquidity and redemption would be subject to separate tests. Under the OCC’s quantitative option, at least 10 percent of outstanding stablecoins would need to be redeemable on the same business day, and at least 30 percent within five business days.
Redemption itself would be at par within two business days of a valid request.
Under stress conditions, the deadline changes. If redemption requests exceed 10 percent of outstanding issuance over a rolling 24-hour period, issuers would have up to seven calendar days to complete redemptions, while notifying the regulator immediately.
The OCC alone sought feedback on more than 200 issues, highlighting how many design choices remain open even at this late stage of the rulemaking. That leaves room for changes in the final text.
The Compliance Clock Starts Later Than July 18
July 18 is a deadline for regulators, not for issuers. Even if agencies publish the rules on time, most obligations do not take effect immediately.
Under the GENIUS Act, the framework becomes effective 120 days after the primary federal regulators publish their final rules, or on January 18, 2027, whichever comes first.
In practice, that means issuers are unlikely to face the new regime before mid-November, even if the rulemaking is completed by the statutory deadline.
Some requirements follow their own timetable. Once FinCEN and OFAC publish their final AML rule, issuers will have 12 months to implement the required compliance programmes.
The longest transition applies to the firms that distribute rather than issue stablecoins.
From July 18, 2028, exchanges, brokers and custodians will no longer be allowed to offer stablecoins in the US unless they are issued by a permitted domestic issuer or a registered foreign issuer.
Not Every Issuer Starts From the Same Position
Circle and Paxos are the furthest along the federal path. Both received conditional national trust bank charters from the OCC in December 2025, placing them inside the federal perimeter before the rules were even proposed.
Ripple has applied for a national trust bank charter and holds RLUSD reserves in Treasuries and money market funds with BNY Mellon as custodian, but its application has yet to be approved.
Tether faces a different set of questions. USDT’s reserves include asset classes that fall outside the proposed list of eligible reserve assets.
Its foreign-issuer path is also uncertain: Treasury would need to determine that the issuer’s home regulatory framework is comparable to the US model.
No jurisdiction has yet received that determination.
In January 2026, Tether launched USA₮, a separate US-market token issued through Anchorage Digital Bank.
State-chartered issuers face another unresolved issue.
Treasury’s framework for determining whether state regimes are “substantially similar” to the federal regime remains in proposed form, and no state has yet been certified.
The Issuer’s Licence Becomes the Broker’s Due Diligence
For brokers and payment firms, the rules matter even if they never issue a stablecoin themselves. Once the Act is in effect, using a stablecoin in the US will increasingly depend on the regulatory status of the issuer behind it.
After the 2028 cutoff, offering a non-permitted token becomes the service provider’s regulatory exposure, not only the issuer’s.
That changes the due diligence question.
A broker accepting stablecoins for client funding or settlement will need to look beyond the token itself and check who issued it, under which licence, and what reserve disclosures stand behind it.
The proposed framework would give firms more standardised information to rely on, including par redemption within two business days, monthly certified reserve reports and a supervised AML programme.
That does not eliminate counterparty risk. Stablecoin holdings carry no FDIC deposit insurance, even when the issuer is bank-affiliated. The risk review moves instead to the issuer’s charter status, reserve reports and compliance controls.
One issue remains unresolved on the service-provider side: whether exchanges can continue offering reward programmes on stablecoin balances without violating the Act’s ban on issuer-paid yield.
Banking groups, including the American Bankers Association and the Bank Policy Institute, argue that exchange-funded rewards undermine the prohibition and accelerate deposit migration; crypto firms maintain that Congress deliberately limited the ban to issuers.
The dispute is playing out in Congress rather than the courts, through the yield provisions of the separate CLARITY Act.
What to Watch After July 18
The next phase will depend first on whether regulators meet the July 18 deadline at all.
If they do, the focus will immediately shift from the proposals to the final text: whether the OCC keeps its quantitative liquidity option, how reserve diversification is handled, and whether the Federal Reserve closes the gap for issuers under its supervision.
Timing will matter as much as substance. Once the primary federal regulators publish the final rules, the 120-day clock begins. That date will determine when issuers must move from preparing against draft proposals to operating under the first federal stablecoin regime.
Ten days remain before the statutory deadline for federal agencies to publish the implementing rules under the GENIUS Act. As of this week, the rulebook is still missing, leaving stablecoin issuers to prepare against proposed texts rather than binding regulations.
Seven federal agencies – the OCC, FDIC, Federal Reserve, NCUA, Treasury, FinCEN and OFAC – are required to complete the stablecoin rulemaking by July 18, one year after the law was signed.
Between December 2025 and June 2026, they released proposals covering capital, reserves, liquidity, redemption, financial crime compliance and credit union-affiliated issuers.
The drafts do not settle the details, but they show the direction of the first federal stablecoin regime: higher capital and liquidity standards, tighter reserve rules, and bank-style compliance obligations for issuers.
The Rulebook is Still in Draft, but the Outline Is Already Clear
The Office of the Comptroller of the Currency (OCC) published the most detailed proposal in February, setting out how federally supervised stablecoin issuers would be licensed, examined and required to manage reserves and redemptions.
In the following months, other agencies filled in separate parts of the framework: bank-affiliated issuers, state regime certification, anti-money laundering controls and sanctions compliance. Comments on the main proposals closed by June 9.
The National Credit Union Administration (NCUA), which oversees credit unions, came later than the other agencies: its proposal for credit union-affiliated stablecoin issuers was published in May, and the comment period closes on July 17, one day before the deadline.
The Federal Reserve has not published a standalone proposal for stablecoin issuers under its supervision, joining only the interagency customer identification proposal released in June. That leaves subsidiaries of state member banks without the same agency-specific roadmap that OCC- and FDIC-supervised issuers already have.
That creates an unusual situation: parts of the statutory framework could become effective before the Federal Reserve finalises its customer-identification rules.
Agencies miss statutory rulemaking deadlines regularly and face no formal penalty for doing so. The practical consequence is timing, covered below.
Trump Signs GENIUS Act Into Law, Setting Stage for Wider Crypto Oversight
Trump’s Genius and Crypto Acts Stall, But He’ll Be Back
What Issuers Will Have to Comply With
The core of the regime sits in the statute itself and will not move. Every permitted issuer must hold 1:1 reserves in eligible assets. Rehypothecation of those reserves is prohibited for most purposes.
Issuers must also publish monthly reserve reports covering reserve composition, outstanding supply and tenor. Those reports must be certified by the CEO and CFO and accompanied by a third-party attestation from a registered accounting firm.
The statute also fixes the financial crime baseline: issuers become financial institutions under the Bank Secrecy Act, the same legal status as a bank.
The FinCEN and OFAC proposal spells out what that requires in practice – board-approved AML programmes, suspicious activity reporting, sanctions screening and the ability to block or freeze tokens when required by law. FinCEN estimates the rules would initially apply to around 50 issuers.
The proposed rules add the prudential detail. The OCC has proposed a $5 million minimum capital floor for new federal issuers, with additional risk-based requirements for larger or more complex firms.
The proposal also narrows what can count as a reserve asset. Eligible assets would include cash, balances at Federal Reserve Banks, insured demand deposits, Treasury bills, and overnight Treasury repos.
Liquidity and redemption would be subject to separate tests. Under the OCC’s quantitative option, at least 10 percent of outstanding stablecoins would need to be redeemable on the same business day, and at least 30 percent within five business days.
Redemption itself would be at par within two business days of a valid request.
Under stress conditions, the deadline changes. If redemption requests exceed 10 percent of outstanding issuance over a rolling 24-hour period, issuers would have up to seven calendar days to complete redemptions, while notifying the regulator immediately.
The OCC alone sought feedback on more than 200 issues, highlighting how many design choices remain open even at this late stage of the rulemaking. That leaves room for changes in the final text.
The Compliance Clock Starts Later Than July 18
July 18 is a deadline for regulators, not for issuers. Even if agencies publish the rules on time, most obligations do not take effect immediately.
Under the GENIUS Act, the framework becomes effective 120 days after the primary federal regulators publish their final rules, or on January 18, 2027, whichever comes first.
In practice, that means issuers are unlikely to face the new regime before mid-November, even if the rulemaking is completed by the statutory deadline.
Some requirements follow their own timetable. Once FinCEN and OFAC publish their final AML rule, issuers will have 12 months to implement the required compliance programmes.
The longest transition applies to the firms that distribute rather than issue stablecoins.
From July 18, 2028, exchanges, brokers and custodians will no longer be allowed to offer stablecoins in the US unless they are issued by a permitted domestic issuer or a registered foreign issuer.
Not Every Issuer Starts From the Same Position
Circle and Paxos are the furthest along the federal path. Both received conditional national trust bank charters from the OCC in December 2025, placing them inside the federal perimeter before the rules were even proposed.
Ripple has applied for a national trust bank charter and holds RLUSD reserves in Treasuries and money market funds with BNY Mellon as custodian, but its application has yet to be approved.
Tether faces a different set of questions. USDT’s reserves include asset classes that fall outside the proposed list of eligible reserve assets.
Its foreign-issuer path is also uncertain: Treasury would need to determine that the issuer’s home regulatory framework is comparable to the US model.
No jurisdiction has yet received that determination.
In January 2026, Tether launched USA₮, a separate US-market token issued through Anchorage Digital Bank.
State-chartered issuers face another unresolved issue.
Treasury’s framework for determining whether state regimes are “substantially similar” to the federal regime remains in proposed form, and no state has yet been certified.
The Issuer’s Licence Becomes the Broker’s Due Diligence
For brokers and payment firms, the rules matter even if they never issue a stablecoin themselves. Once the Act is in effect, using a stablecoin in the US will increasingly depend on the regulatory status of the issuer behind it.
After the 2028 cutoff, offering a non-permitted token becomes the service provider’s regulatory exposure, not only the issuer’s.
That changes the due diligence question.
A broker accepting stablecoins for client funding or settlement will need to look beyond the token itself and check who issued it, under which licence, and what reserve disclosures stand behind it.
The proposed framework would give firms more standardised information to rely on, including par redemption within two business days, monthly certified reserve reports and a supervised AML programme.
That does not eliminate counterparty risk. Stablecoin holdings carry no FDIC deposit insurance, even when the issuer is bank-affiliated. The risk review moves instead to the issuer’s charter status, reserve reports and compliance controls.
One issue remains unresolved on the service-provider side: whether exchanges can continue offering reward programmes on stablecoin balances without violating the Act’s ban on issuer-paid yield.
Banking groups, including the American Bankers Association and the Bank Policy Institute, argue that exchange-funded rewards undermine the prohibition and accelerate deposit migration; crypto firms maintain that Congress deliberately limited the ban to issuers.
The dispute is playing out in Congress rather than the courts, through the yield provisions of the separate CLARITY Act.
What to Watch After July 18
The next phase will depend first on whether regulators meet the July 18 deadline at all.
If they do, the focus will immediately shift from the proposals to the final text: whether the OCC keeps its quantitative liquidity option, how reserve diversification is handled, and whether the Federal Reserve closes the gap for issuers under its supervision.
Timing will matter as much as substance. Once the primary federal regulators publish the final rules, the 120-day clock begins. That date will determine when issuers must move from preparing against draft proposals to operating under the first federal stablecoin regime.