No Result
View All Result
  • Login
Wednesday, September 23, 2026
FeeOnlyNews.com
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading
No Result
View All Result
FeeOnlyNews.com
No Result
View All Result
Home Markets

Iron Mountain (IRM) Has a Storage-Cash-Flow and Data-Center Expansion Story Bigger Than a Paper-Records REIT Label

by FeeOnlyNews.com
3 months ago
in Markets
Reading Time: 4 mins read
A A
0
Iron Mountain (IRM) Has a Storage-Cash-Flow and Data-Center Expansion Story Bigger Than a Paper-Records REIT Label
Share on FacebookShare on TwitterShare on LInkedIn


Iron Mountain is still often treated like a legacy paper-records REIT with modest growth attached. Its filings point to a more interesting structure: a recurring-storage cash flow base that helps finance expansion in data centers, digital services, and asset lifecycle management. In Q1 2026, total revenue rose to $1.936 billion from $1.593 billion a year earlier, cash flow from operating activities increased to $338.6 million from $197.3 million, and cash and cash equivalents reached $250.7 million at quarter-end. That is not the profile of a business living only off a declining box-storage franchise.

Thesis and why the paper-records REIT framing misses the platform story

The old label misses how Iron Mountain’s revenue model is built. In its FY2025 annual report, the company said a majority of revenue is recurring in nature. Its contracted storage rental agreements in Records Management generally run one to five years, while the weighted average lease expiration in the Global Data Center Business was 10.3 years as of December 31, 2025.

That mix matters because it pairs durability with reinvestment optionality. Records storage is not glamorous, but it throws off recurring revenue from physical volumes that customers typically retain for many years. The annual report said Iron Mountain stored more than 740 million cubic feet of physical volume at year-end 2025. At the same time, the company’s Global Data Center Business serves enterprise and hyperscale infrastructure demand with much longer lease duration than the legacy records business alone would suggest.

The result is a platform that looks less like a static records landlord and more like a business reallocating dependable cash flows into faster-growth infrastructure and services.

Storage cash flow, service revenue, and data-center expansion

The bridge between the old business and the newer one is visible in the quarterly report. Iron Mountain said its organic storage rental revenue growth is driven by revenue management in its Global RIM business and by growth in its Global Data Center Business, primarily through lease commencements. It also said organic service revenue growth is being driven by digital offerings, traditional records-management services, and asset lifecycle management.

That helps explain why the company should not be reduced to a paper-storage multiple. In Q1 2026, total revenue was $1.936 billion, and storage rental revenue associated with the Global Data Center Business alone was $252.5 million, up from $172.9 million a year earlier. That means a meaningful and growing portion of the recurring revenue base is tied directly to digital infrastructure, not just physical document retention.

The FY2025 annual report provides the broader funding context. Total revenue for 2025 reached $6.902 billion, and cash flow from operating activities was $1.340 billion. The same filing also showed $1.216 billion of real estate additions during 2025, evidence that Iron Mountain is still putting substantial capital behind facility expansion while leaning on a recurring revenue base to support that investment.

This is the core of the thesis: legacy storage economics are not merely being harvested. They are being used to underwrite a broader infrastructure and services portfolio.

Capital intensity, leverage, competition, and risks to the thesis

The obvious risk is that this strategy is capital intensive. Data-center growth requires power, land, construction, and disciplined leasing. The annual report’s $1.216 billion of real estate additions in 2025 is a reminder that investors are not buying a light-capex software business. If lease-up slows or project timing slips, returns on new builds can disappoint even if the legacy records business remains stable.

There is also execution risk in the mix shift itself. The quarterly report makes clear that storage rental growth in the legacy business still depends partly on revenue management rather than large physical-volume growth, while service growth depends on continued adoption of digital offerings and asset lifecycle management. If digital and service lines grow more slowly than expected, the “platform” story could start looking more like a mature storage business again.

Competition matters too. The data-center market is more competitive and capital hungry than records management, and longer leases do not eliminate development risk. Iron Mountain’s advantage is that it does not need to fund that growth from a cold start. Its recurring storage economics and operating cash generation give it a base that many pure-play expansion stories lack.

Investor takeaway and what to watch in leasing, margins, and cash generation

Iron Mountain looks stronger when viewed as a cash-flow allocator rather than as a paper-records relic. The business still benefits from highly recurring records-management revenue, but it is increasingly using that durability to expand in data centers and adjacent services. Q1 2026 showed the operating shape of that model: $1.936 billion of revenue, $338.6 million of operating cash flow, and $252.5 million of data-center storage rental revenue in the quarter. The FY2025 annual report added the structural context: $6.902 billion of annual revenue, $1.340 billion of operating cash flow, more than 740 million cubic feet of stored physical volume, and a 10.3-year weighted average lease expiration in data centers.

For investors, the key question is whether Iron Mountain can keep converting the dependability of the legacy storage base into attractive returns on newer infrastructure and service growth. If leasing stays healthy, margins remain resilient, and cash generation continues to cover meaningful expansion spending, the company deserves to trade as more than a paper-records REIT.

Key Signals for Investors

Data-center leasing and the pace of lease commencements.
Storage rental growth versus service revenue growth.
Cash flow from operating activities relative to expansion spending.
Evidence that digital and asset lifecycle offerings are scaling alongside records management.
Whether the recurring revenue base continues to support margin resilience through the portfolio shift.

Source link

Tags: BiggerdatacenterexpansionIRMIronlabelMountainPaperRecordsREITStorageCashFlowStory
ShareTweetShare
Previous Post

SpaceX seeing interest from short sellers, but most afraid to go against Musk

Next Post

US Stock: S&P, Nasdaq end lower on semiconductor selloff as AI spending concerns mount

Related Posts

All signs are pointing to the total and imminent collapse of the United States housing market.

All signs are pointing to the total and imminent collapse of the United States housing market.

by FeeOnlyNews.com
August 7, 2026
0

All signs are pointing to the total and imminent collapse of the United States housing market.What is about to happen...

Cities holding up to 3 million people found under Amazon rain forest

Cities holding up to 3 million people found under Amazon rain forest

by FeeOnlyNews.com
August 7, 2026
0

Archaeologists have officially discovered a massive, completely lost ancient civilization hidden deep beneath the Amazon rainforest using advanced LiDAR laser...

nLIGHT Releases Q2 2026 Financial Results

nLIGHT Releases Q2 2026 Financial Results

by FeeOnlyNews.com
August 7, 2026
0

AlphaStreet Newsdesk powered by AlphaStreet Intelligence LASR|EPS $0.15 vs $0.14 est (+7.1%)|Rev $82.6M|Net Loss $1.3M Q2 2026 non-GAAP earnings at...

The  Burrito Debate Reveals GOP’s Affordability Rift

The $20 Burrito Debate Reveals GOP’s Affordability Rift

by FeeOnlyNews.com
August 7, 2026
0

Sometimes a burrito isn’t just a burrito. What started as a complaint about a $20 burrito has turned into one...

Doximity shares double. Here’s what’s driving it 

Doximity shares double. Here’s what’s driving it 

by FeeOnlyNews.com
August 7, 2026
0

Doximity at the New York Stock Exchange for its initial public offering on June 24, 2021.Source: NYSEShares of medical platform...

E.W. Scripps Q2 2026 Loss Widens to -.68/Share, Revenue Down 9%

E.W. Scripps Q2 2026 Loss Widens to -$12.68/Share, Revenue Down 9%

by FeeOnlyNews.com
August 7, 2026
0

AlphaStreet Newsdesk powered by AlphaStreet Intelligence SSP|Loss Per Share $12.68 vs -$0.40 est (-3070.0%)|Rev $490.4M|Net Loss $1.15B Stock $2.95 (+2.8%)...

Next Post
US Stock: S&P, Nasdaq end lower on semiconductor selloff as AI spending concerns mount

US Stock: S&P, Nasdaq end lower on semiconductor selloff as AI spending concerns mount

Jack Henry (JKHY) Has a Core-Banking and Payments Workflow Engine Bigger Than a Regional-Bank Proxy Narrative

Jack Henry (JKHY) Has a Core-Banking and Payments Workflow Engine Bigger Than a Regional-Bank Proxy Narrative

  • Trending
  • Comments
  • Latest
MEXC Lists Ondo Yield Asset As Tokenized Treasury Demand Grows

MEXC Lists Ondo Yield Asset As Tokenized Treasury Demand Grows

July 3, 2026
Delek Logistics Partners Reports alt=

Delek Logistics Partners Reports $0.54 EPS for Q2 FY26

August 5, 2026
The AI Race With China Is a Lie Told by Big Tech to Justify the Data Center Invasion

The AI Race With China Is a Lie Told by Big Tech to Justify the Data Center Invasion

July 27, 2026
Vanilla’s approach to better software for family offices: Listen first, build second

Vanilla’s approach to better software for family offices: Listen first, build second

July 2, 2026
Supreme Court’s birthright citizenship ruling hands the U.S. economy a .7 trillion win

Supreme Court’s birthright citizenship ruling hands the U.S. economy a $7.7 trillion win

July 1, 2026
Building The Profession Through (Joining) Membership Associations: How Financial Advisors Can Benefit From Being Active With FPA

Building The Profession Through (Joining) Membership Associations: How Financial Advisors Can Benefit From Being Active With FPA

June 8, 2026
Advanced Micro Devices (AMD) Price Prediction: How Much a ,000 Investment Could Be Worth by 2031

Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031

0
Cities holding up to 3 million people found under Amazon rain forest

Cities holding up to 3 million people found under Amazon rain forest

0
Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

0
Bybit Uses Tokenised Equities as Underlyings for Structured Yield

Bybit Uses Tokenised Equities as Underlyings for Structured Yield

0
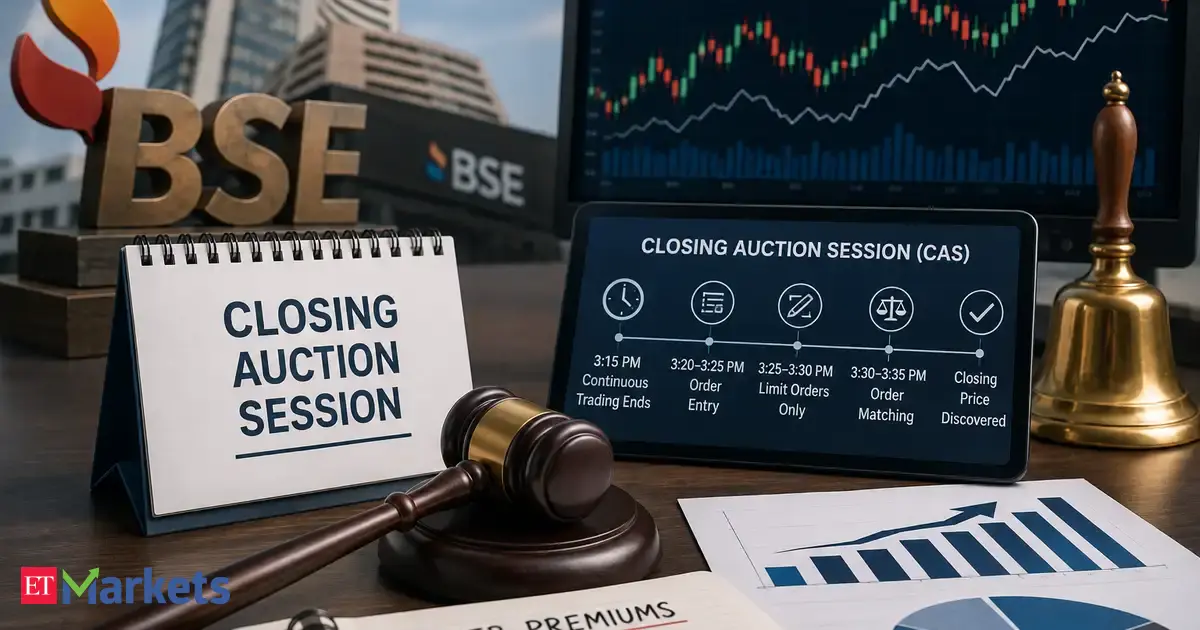
Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

0
Vaxart outlines Phase IIb COVID-19 top line data in first half of 2027 backed by BARDA funding (OTCMKTS:VXRT)

Vaxart outlines Phase IIb COVID-19 top line data in first half of 2027 backed by BARDA funding (OTCMKTS:VXRT)

0
Advanced Micro Devices (AMD) Price Prediction: How Much a ,000 Investment Could Be Worth by 2031

Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031

August 8, 2026
Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

August 8, 2026
Vanguard Chief Economist: AI and jobs, still in an ATM phase

Vanguard Chief Economist: AI and jobs, still in an ATM phase

August 8, 2026
Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

August 8, 2026
Democrats’ Affordability Message Misses a Key Expense—Student Debt

Democrats’ Affordability Message Misses a Key Expense—Student Debt

August 8, 2026
Banks or NBFCs? DSP’s Preethi R S explains where she sees the best opportunities

Banks or NBFCs? DSP’s Preethi R S explains where she sees the best opportunities

August 8, 2026
FeeOnlyNews.com

Get the latest news and follow the coverage of Business & Financial News, Stock Market Updates, Analysis, and more from the trusted sources.

CATEGORIES

  • Business
  • Cryptocurrency
  • Economy
  • Financial Planning
  • Investing
  • Market Analysis
  • Markets
  • Money
  • Personal Finance
  • Startups
  • Stock Market
  • Trading

LATEST UPDATES

  • Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031
  • Republican Party Displacement | Mises Institute
  • Vanguard Chief Economist: AI and jobs, still in an ATM phase
  • Our Great Privacy Policy
  • Terms of Use, Legal Notices & Disclaimers
  • About Us
  • Contact Us

Copyright © 2022-2024 All Rights Reserved
See articles for original source and related links to external sites.

Welcome Back!

Sign In with Facebook
Sign In with Google
Sign In with Linked In
OR

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In
No Result
View All Result
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading

Copyright © 2022-2024 All Rights Reserved
See articles for original source and related links to external sites.