No Result
View All Result
  • Login
Monday, September 14, 2026
FeeOnlyNews.com
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading
No Result
View All Result
FeeOnlyNews.com
No Result
View All Result
Home Investing

Investment Behavior Is a Design Problem, Not an Information Problem

by FeeOnlyNews.com
6 months ago
in Investing
Reading Time: 4 mins read
A A
0
Investment Behavior Is a Design Problem, Not an Information Problem
Share on FacebookShare on TwitterShare on LInkedIn


For decades, the dominant explanation for low investment participation and suboptimal portfolio choices has been a lack of information. Investors, we are told, do not invest well because they do not understand risk, returns, or financial products. The implied solution is therefore to provide more education, clearer disclosures, and better data.

Yet despite significant investments in financial literacy programs, improved transparency, and broader access to markets, many of the same behavioral patterns persist. Investors remain overly conservative in their asset allocation, exit markets during periods of volatility, delay participation despite rising income, and display deep mistrust of financial institutions.

These outcomes are observed not only among retail investors, but also among highly educated and financially sophisticated individuals. The consequences are measurable: investors hold excess cash during expansions, sell into drawdowns, and systematically erode long-term returns.

This begs the question for all investment professionals serving retail investors: What if information, while necessary, is not sufficient to change behavior?

Why Information Isn’t Enough

Traditional financial theory assumes that once individuals are properly informed, they will act in a manner consistent with rational optimization. In practice, however, investment decisions are rarely made in neutral or controlled environments. They are made under uncertainty, emotional stress, social influence, and time pressure.

When markets decline sharply, investors do not calmly reassess expected returns and correlations; they experience fear. When volatility rises, risk is not processed as a statistical distribution but as a psychological threat. In such contexts, additional information often fails to improve decision-making and can, in some cases, aggravate anxiety and inaction.

Empirical evidence from behavioral finance supports this observation. Individuals are loss averse, overweight recent experiences, discount future outcomes, and rely on heuristics when faced with complexity. These tendencies persist even among financially literate investors. Firms that ignore this reality will continue to attribute client outcomes to behavior rather than to the systems that shape it.

Behavior Follows Design

One of the most robust insights from behavioral research is that behavior responds strongly to context. Defaults, framing, choice architecture, and institutional signals all influence decisions often more powerfully than information itself.

For example, participation rates in retirement plans vary dramatically depending on whether enrollment is opt-in or opt-out, even when contribution options and disclosures are identical. Similarly, investors’ willingness to hold risky assets is affected by how performance information is presented, the frequency of feedback, and the perceived behavior of peers.

These findings suggest that investment outcomes are shaped not only by what investors know, but by how investment systems are designed. Decisions are embedded in environments that either amplify or dampen behavioral biases.

Despite this, many financial systems continue to assume high levels of self-control, foresight, and emotional resilience from participants. Products are designed with an implicit expectation of discipline. Advice frameworks assume follow-through. Regulation often assumes compliance once rules are clearly communicated. When outcomes fall short, the response is frequently to intensify education efforts rather than to reconsider the underlying design assumptions.

From Education to Design

Recognizing the limits of information does not diminish the role of investment professionals. It reframes it. The question shifts from “How much more can we explain?” to “How well are decisions being designed?”

This reframing has important implications across the investment ecosystem: For asset managers, product success should not be evaluated solely on performance metrics. The behavioral journey of the investor such as how they enter, stay invested, and react to volatility is equally important.

Products that are theoretically optimal but behaviorally fragile are unlikely to deliver intended outcomes at scale. For financial advisors, effectiveness depends not only on the quality of recommendations, but on when and how advice is delivered. Timing, framing, and emotional context shape whether advice is acted upon, particularly during periods of market stress. For policymakers and regulators, participation, trust, and inclusion are not primarily communication challenges. They are institutional design challenges. Rules and safeguards influence behavior not only through enforcement, but through the signals they send about trust, stability, and fairness.

Designing for Real Investors

A design-oriented approach to investment behavior does not reject rationality; it recognizes its limits. It acknowledges that humans operate with bounded rationality and predictable biases, and that systems should be built accordingly. This means asking different questions:

Where can defaults support long-term behavior rather than short-term impulses?

How can choice sets be simplified without reducing meaningful options?

What forms of friction are helpful, and which are harmful?

How do institutional rules affect trust and perceived legitimacy, especially in emerging markets?

How do we reframe financial education as support, not a solution?

These are not theoretical concerns. They are practical design questions with direct implications for asset allocation, market participation, and financial stability.

Conclusion

The persistent gap between investment knowledge and investment behavior suggests that the problem is not simply one of education. Information matters, but it operates within environments that shape decisions. If investment outcomes consistently fall short of intent, the critical question is not why investors fail to act rationally. It is whether the products, advice frameworks, and institutional rules they encounter are designed for real human behavior. Improving investment outcomes, therefore, requires a shift in focus from explaining more to designing better.

From assuming rational agents to working with predictable behavior. From treating behavior as noise to recognizing it as a central feature of financial decision-making. This shift is not optional. It is increasingly essential for investment professionals seeking durable outcomes in an uncertain world.
Source link

Tags: BehaviorDesignInformationInvestmentproblem
ShareTweetShare
Previous Post

The Strange Pace of Progress

Next Post

9 Ways to Use the Medicare Plan Finder Without Getting Overwhelmed

Related Posts

Even China is finding economic growth harder to come by these days

Even China is finding economic growth harder to come by these days

by FeeOnlyNews.com
August 7, 2026
0

via notayesmanseconomicsThere has been a flurry of background economic news from China this week and we can start with an...

Those That Were Considered To Be “Dirt Poor” In 1987 Would Be Considered To Be Very Wealthy In 2026

Those That Were Considered To Be “Dirt Poor” In 1987 Would Be Considered To Be Very Wealthy In 2026

by FeeOnlyNews.com
August 6, 2026
0

by MichaelAmericans are facing the longest and most painful affordability crisis in our entire history, and young people are being...

The Fuse is Lit on One of the World’s Largest Debt Bombs

The Fuse is Lit on One of the World’s Largest Debt Bombs

by FeeOnlyNews.com
August 6, 2026
0

via gainspainscapitalYesterday I noted that Japan was on the verge of a debt crisis.By quick way of review…After 30+ years...

2026 Dividend Aristocrats List | Updated Daily

2026 Dividend Aristocrats List | Updated Daily

by FeeOnlyNews.com
August 5, 2026
0

Article updated on August 5th, 2026 by Nikolaos SismanisSpreadsheet data updated daily The Dividend Aristocrats are an elite group of...

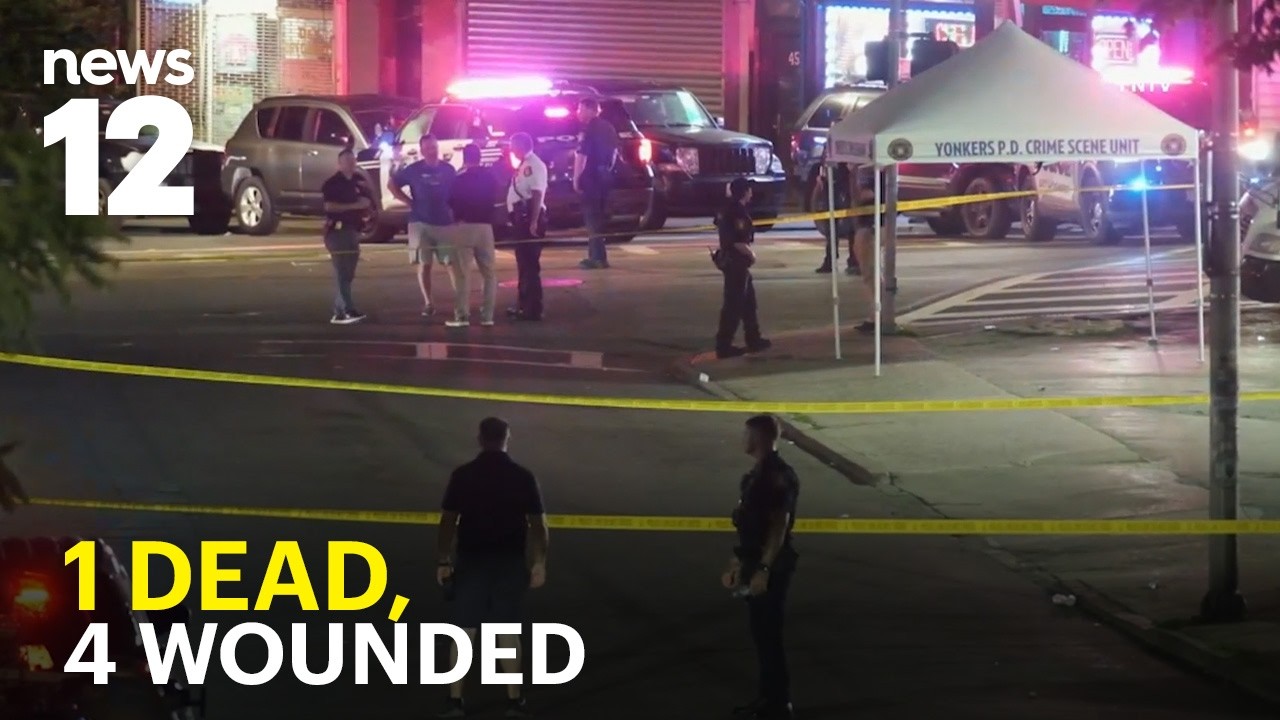
15-year-old boy opens fire on Yonkers, New York street corner kills one wounds four teens

15-year-old boy opens fire on Yonkers, New York street corner kills one wounds four teens

by FeeOnlyNews.com
August 5, 2026
0

Share this storyA shooting in Yonkers on Sunday August 2 left five people shot. One 20-year-old man died. Four teens...

How to Build Your Own Real Estate Investing Team (From Scratch)

How to Build Your Own Real Estate Investing Team (From Scratch)

by FeeOnlyNews.com
August 5, 2026
0

Real estate investing is a team sport. You can buy great rental properties in great neighborhoods and still fail—all because...

Next Post
9 Ways to Use the Medicare Plan Finder Without Getting Overwhelmed

9 Ways to Use the Medicare Plan Finder Without Getting Overwhelmed

School Financial Literacy Programs That Qualify for CRA Credit

School Financial Literacy Programs That Qualify for CRA Credit

  • Trending
  • Comments
  • Latest
Bitcoin and ethereum prices today, Friday, August 7, 2026: Crypto prices moving higher following July jobs report

Bitcoin and ethereum prices today, Friday, August 7, 2026: Crypto prices moving higher following July jobs report

August 7, 2026
MEXC Lists Ondo Yield Asset As Tokenized Treasury Demand Grows

MEXC Lists Ondo Yield Asset As Tokenized Treasury Demand Grows

July 3, 2026
Delek Logistics Partners Reports alt=

Delek Logistics Partners Reports $0.54 EPS for Q2 FY26

August 5, 2026
Onkure Therapeutics Releases Q2 2026 Financial Results

Onkure Therapeutics Releases Q2 2026 Financial Results

August 4, 2026
Thryv outlines M run-rate savings while revising 2026 SaaS adjusted EBITDA to M-M (NASDAQ:THRY)

Thryv outlines $60M run-rate savings while revising 2026 SaaS adjusted EBITDA to $42M-$44M (NASDAQ:THRY)

August 4, 2026
My Thoughts on Going All In

My Thoughts on Going All In

August 4, 2026
Advanced Micro Devices (AMD) Price Prediction: How Much a ,000 Investment Could Be Worth by 2031

Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031

0
Cities holding up to 3 million people found under Amazon rain forest

Cities holding up to 3 million people found under Amazon rain forest

0
Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

0
Bybit Uses Tokenised Equities as Underlyings for Structured Yield

Bybit Uses Tokenised Equities as Underlyings for Structured Yield

0
Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

0
Vaxart outlines Phase IIb COVID-19 top line data in first half of 2027 backed by BARDA funding (OTCMKTS:VXRT)

Vaxart outlines Phase IIb COVID-19 top line data in first half of 2027 backed by BARDA funding (OTCMKTS:VXRT)

0
Advanced Micro Devices (AMD) Price Prediction: How Much a ,000 Investment Could Be Worth by 2031

Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031

August 8, 2026
Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

August 8, 2026
Vanguard Chief Economist: AI and jobs, still in an ATM phase

Vanguard Chief Economist: AI and jobs, still in an ATM phase

August 8, 2026
Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

August 8, 2026
Democrats’ Affordability Message Misses a Key Expense—Student Debt

Democrats’ Affordability Message Misses a Key Expense—Student Debt

August 8, 2026
Banks or NBFCs? DSP’s Preethi R S explains where she sees the best opportunities

Banks or NBFCs? DSP’s Preethi R S explains where she sees the best opportunities

August 8, 2026
FeeOnlyNews.com

Get the latest news and follow the coverage of Business & Financial News, Stock Market Updates, Analysis, and more from the trusted sources.

CATEGORIES

  • Business
  • Cryptocurrency
  • Economy
  • Financial Planning
  • Investing
  • Market Analysis
  • Markets
  • Money
  • Personal Finance
  • Startups
  • Stock Market
  • Trading

LATEST UPDATES

  • Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031
  • Republican Party Displacement | Mises Institute
  • Vanguard Chief Economist: AI and jobs, still in an ATM phase
  • Our Great Privacy Policy
  • Terms of Use, Legal Notices & Disclaimers
  • About Us
  • Contact Us

Copyright © 2022-2024 All Rights Reserved
See articles for original source and related links to external sites.

Welcome Back!

Sign In with Facebook
Sign In with Google
Sign In with Linked In
OR

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In
No Result
View All Result
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading

Copyright © 2022-2024 All Rights Reserved
See articles for original source and related links to external sites.