No Result
View All Result
  • Login
Wednesday, September 23, 2026
FeeOnlyNews.com
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading
No Result
View All Result
FeeOnlyNews.com
No Result
View All Result
Home Money

7 Homeowners Insurance Questions Every Retiree Should Ask Before the Next Big Storm

by FeeOnlyNews.com
2 months ago
in Money
Reading Time: 6 mins read
A A
0
7 Homeowners Insurance Questions Every Retiree Should Ask Before the Next Big Storm
Share on FacebookShare on TwitterShare on LInkedIn


Reviewing your homeowners insurance before storm season peaks can help retirees uncover costly coverage gaps, understand deductibles, and better protect their savings. Jeff McCollough/Shutterstock

After a major storm, many homeowners discover an expensive truth: having homeowners insurance doesn’t necessarily mean every type of damage is covered. Some retirees are surprised to learn they have a separate hurricane deductible, no flood coverage, or dwelling limits that haven’t kept up with today’s rebuilding costs. Those discoveries often happen after the damage is already done, when changing your policy is no longer an option. Spending 30 minutes reviewing your coverage before severe weather arrives could save thousands of dollars (and a tremendous amount of stress) later. Here is a look at seven questions that every homeowner (yes, you too) should ask before the next storm.

1. Does My Policy Cover Every Type of Storm Damage?

Many retirees are surprised to learn that standard homeowners insurance doesn’t cover every natural disaster. Most policies cover wind, hail, lightning, and fire, but flooding typically requires a separate flood insurance policy. Earthquake damage is also excluded unless additional coverage is purchased. If you live near the coast or in an area prone to flash flooding, ask your insurance agent exactly which weather events are covered and which require separate protection. The National Association of Insurance Commissioners (NAIC) has recommended reviewing your policy before disaster strikes.

2. Could My Deductible Be Much Higher Than I Expect?

Imagine a retiree whose home is insured for $400,000 with a 2% named-storm deductible. After a hurricane damages the roof, the homeowner is responsible for the first $8,000 of repairs before insurance begins paying. That’s a surprise many people don’t discover until they file a claim.

Many homeowners know their standard deductible but overlook special storm deductibles. Some policies include separate wind, hail, or named storm deductibles that are calculated as a percentage of your home’s insured value instead of a flat dollar amount. For a $350,000 home, even a 2% named storm deductible could leave you responsible for $7,000 before insurance begins paying. Reviewing this number now allows retirees to adjust emergency savings or explore different deductible options before severe weather arrives. Named storm deductibles can range from 1% to 10% depending on the policy and location.

3. Is My Home Insured for Today’s Rebuilding Costs?

Many homeowners focus on what their home could sell for, but insurers care about something different: what it would cost to rebuild from the ground up after a total loss. Labor shortages, higher material costs, and updated building codes have pushed reconstruction costs higher in many parts of the country. Even homeowners whose property values have stayed relatively stable may find they’re underinsured if their dwelling coverage hasn’t been reviewed recently.

Housing prices and construction costs have changed dramatically over the past several years. Even if your home’s market value hasn’t increased significantly, rebuilding costs may have climbed because of labor shortages and higher material prices. Ask your insurance company whether your dwelling coverage still reflects current replacement costs rather than what your home was worth years ago. This simple conversation can prevent an unpleasant surprise if a major storm causes extensive damage. The NAIC recommends reviewing replacement-cost coverage regularly to keep pace with rebuilding expenses.

4. Would Flooding Leave Me Completely Unprotected?

One of the most common claim surprises occurs after hurricanes, when homeowners discover that wind damage is generally covered, but storm surge or rising floodwater is not. If water enters your home from the ground up, standard homeowners insurance typically won’t pay for the damage. That’s why FEMA and insurance experts recommend evaluating flood insurance well before hurricane season, since most National Flood Insurance Program policies include a 30-day waiting period before coverage begins.

5. What Documentation Should I Have Before a Storm Hits?

One of the smartest things retirees can do costs almost nothing. Walk through your home with a smartphone and photograph every room, valuable item, appliance, and major improvement before severe weather arrives. Save receipts for expensive purchases and store digital copies of important documents in cloud storage or another secure location. If a claim becomes necessary, detailed documentation can speed up the claims process and reduce disagreements over what was damaged. Consumer insurance experts also recommend creating a complete home inventory before disaster strikes.

6. Will My Policy Pay for Temporary Living Expenses?

If a major storm makes your home unlivable, you’ll still need somewhere to stay. Many homeowners policies include “additional living expenses” coverage that helps pay for hotel stays, temporary rentals, restaurant meals, and certain other necessary costs while repairs are completed. However, every policy has different limits and conditions, so retirees shouldn’t assume unlimited assistance is available.

Ask your insurer exactly how Additional Living Expenses (ALE) coverage works. Does it pay for hotel rooms? Short-term rentals? Pet boarding? Laundry? Restaurant meals? Is there a dollar limit or a time limit? Reviewing this coverage now can provide valuable peace of mind before severe weather begins.

7. Are There Discounts or Improvements That Could Lower My Premium?

Storm preparation isn’t only about avoiding losses. It may also reduce insurance costs. Some insurers offer discounts for impact-resistant roofing, storm shutters, security systems, updated electrical systems, or bundling home and auto insurance. Others reward homeowners who maintain newer roofs or make other protective upgrades that reduce claim risk. Ask your insurance representative which improvements qualify for premium reductions before investing in upgrades. Even modest annual savings can add up over the course of retirement while making your home more resilient during severe weather.

Bonus Question: Has Inflation Changed What My Policy Should Cover?

While you may not consider it immediately, inflation does have an impact on insurance as well. When things cost more to replace, they also typically cost more to insure. That being said, you should ask your insurer about:

replacement costs
inflation guard endorsements
code upgrades
ordinance/law coverage

A Policy Review Today Could Protect Years of Retirement Savings

What homeowners should do before a storm hits infographic

Most retirees spend years building financial security, yet many haven’t looked closely at their homeowners insurance since they first bought the policy. Storm season is one of the best reminders to revisit that coverage before severe weather threatens your community. A short conversation with your insurance agent today could uncover outdated coverage limits, unexpected deductibles, or discounts that lower your premium while improving your protection. Even if your policy doesn’t need major changes, knowing exactly what it covers can provide something every retiree values: peace of mind when the forecast turns severe.

Have you reviewed your homeowners insurance recently, or have you ever been surprised by something your policy didn’t cover? Share your experience in the comments below.

What to Read Next

Why Your Insulin Price Could Change Even When Your Insurance Plan Doesn’t

5 Home-Energy Assistance Documents Seniors May Need Before Applications Open

Exclusive: What a Former Burglar Says Are the Best (and Worst) Places to Hide Money at Home


Source link

Tags: bigHomeownersInsuranceQuestionsretireeStorm
ShareTweetShare
Previous Post

FOUR Big Tide Laundry Detergents for only $10.72 each, shipped (Plus, Tide Pods deal)!

Next Post

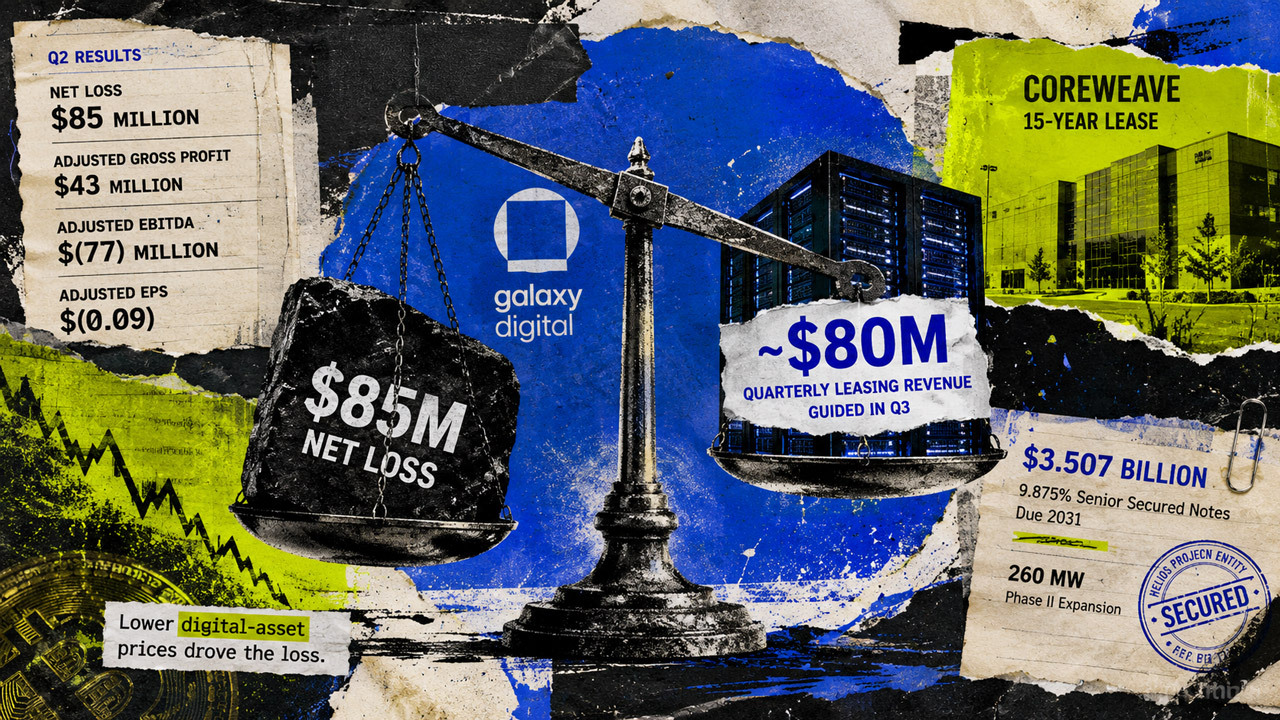
Galaxy Digital: $85M Q2 loss tests its $80M-a-quarter AI lease

Related Posts

6 Part-Time Jobs Retirees Can Explore Before the Holiday Hiring Rush

6 Part-Time Jobs Retirees Can Explore Before the Holiday Hiring Rush

by FeeOnlyNews.com
August 7, 2026
0

The weeks before the holiday hiring rush can be a surprisingly good time for retirees to decide whether a little...

Medicare Deadlines New Retirees Should Put on the Calendar Before Leaving Work

Medicare Deadlines New Retirees Should Put on the Calendar Before Leaving Work

by FeeOnlyNews.com
August 7, 2026
0

A 65-year-old retiring in November may have a completely different Medicare timeline from a 68-year-old leaving an employer health plan...

8 Side Effects of Aging That No One Prepares You For

8 Side Effects of Aging That No One Prepares You For

by FeeOnlyNews.com
August 7, 2026
0

Aging is often portrayed as a graceful journey filled with wisdom, leisure, and newfound freedom. While those aspects can certainly...

Stock news for investors: Quarterly earnings from Telus, Shopify, BCE, and more

Stock news for investors: Quarterly earnings from Telus, Shopify, BCE, and more

by FeeOnlyNews.com
August 6, 2026
0

The company reported a loss attributable to common shareholders of $1.8 billion or $1.17 per share for the quarter ended...

The world’s largest corporate holder of Bitcoin has been selling—should you be concerned?

The world’s largest corporate holder of Bitcoin has been selling—should you be concerned?

by FeeOnlyNews.com
August 6, 2026
0

While selling BTC is not alarming in itself, it seems to go against Executive Chairman Micheal Saylor’s public image as...

7 Warning Signs an Older Adult May Be Under Financial Pressure

7 Warning Signs an Older Adult May Be Under Financial Pressure

by FeeOnlyNews.com
August 6, 2026
0

It often starts with what seems like a harmless favor. A relative offers to help pay bills online. A new...

Next Post
Galaxy Digital: M Q2 loss tests its M-a-quarter AI lease

Galaxy Digital: $85M Q2 loss tests its $80M-a-quarter AI lease

Bitcoin Drops As US Initial Jobless Claims Decline Amid Fed Rate Hike Fears

Bitcoin Drops As US Initial Jobless Claims Decline Amid Fed Rate Hike Fears

  • Trending
  • Comments
  • Latest
MEXC Lists Ondo Yield Asset As Tokenized Treasury Demand Grows

MEXC Lists Ondo Yield Asset As Tokenized Treasury Demand Grows

July 3, 2026
Delek Logistics Partners Reports alt=

Delek Logistics Partners Reports $0.54 EPS for Q2 FY26

August 5, 2026
The AI Race With China Is a Lie Told by Big Tech to Justify the Data Center Invasion

The AI Race With China Is a Lie Told by Big Tech to Justify the Data Center Invasion

July 27, 2026
Vanilla’s approach to better software for family offices: Listen first, build second

Vanilla’s approach to better software for family offices: Listen first, build second

July 2, 2026
Supreme Court’s birthright citizenship ruling hands the U.S. economy a .7 trillion win

Supreme Court’s birthright citizenship ruling hands the U.S. economy a $7.7 trillion win

July 1, 2026
Building The Profession Through (Joining) Membership Associations: How Financial Advisors Can Benefit From Being Active With FPA

Building The Profession Through (Joining) Membership Associations: How Financial Advisors Can Benefit From Being Active With FPA

June 8, 2026
Advanced Micro Devices (AMD) Price Prediction: How Much a ,000 Investment Could Be Worth by 2031

Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031

0
Cities holding up to 3 million people found under Amazon rain forest

Cities holding up to 3 million people found under Amazon rain forest

0
Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

0
Bybit Uses Tokenised Equities as Underlyings for Structured Yield

Bybit Uses Tokenised Equities as Underlyings for Structured Yield

0
Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

0
Vaxart outlines Phase IIb COVID-19 top line data in first half of 2027 backed by BARDA funding (OTCMKTS:VXRT)

Vaxart outlines Phase IIb COVID-19 top line data in first half of 2027 backed by BARDA funding (OTCMKTS:VXRT)

0
Advanced Micro Devices (AMD) Price Prediction: How Much a ,000 Investment Could Be Worth by 2031

Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031

August 8, 2026
Republican Party Displacement | Mises Institute

Republican Party Displacement | Mises Institute

August 8, 2026
Vanguard Chief Economist: AI and jobs, still in an ATM phase

Vanguard Chief Economist: AI and jobs, still in an ATM phase

August 8, 2026
Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

Explained: How BSE traded fewer contracts after CAS but premiums rose 75% in first week

August 8, 2026
Democrats’ Affordability Message Misses a Key Expense—Student Debt

Democrats’ Affordability Message Misses a Key Expense—Student Debt

August 8, 2026
Banks or NBFCs? DSP’s Preethi R S explains where she sees the best opportunities

Banks or NBFCs? DSP’s Preethi R S explains where she sees the best opportunities

August 8, 2026
FeeOnlyNews.com

Get the latest news and follow the coverage of Business & Financial News, Stock Market Updates, Analysis, and more from the trusted sources.

CATEGORIES

  • Business
  • Cryptocurrency
  • Economy
  • Financial Planning
  • Investing
  • Market Analysis
  • Markets
  • Money
  • Personal Finance
  • Startups
  • Stock Market
  • Trading

LATEST UPDATES

  • Advanced Micro Devices (AMD) Price Prediction: How Much a $5,000 Investment Could Be Worth by 2031
  • Republican Party Displacement | Mises Institute
  • Vanguard Chief Economist: AI and jobs, still in an ATM phase
  • Our Great Privacy Policy
  • Terms of Use, Legal Notices & Disclaimers
  • About Us
  • Contact Us

Copyright © 2022-2024 All Rights Reserved
See articles for original source and related links to external sites.

Welcome Back!

Sign In with Facebook
Sign In with Google
Sign In with Linked In
OR

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In
No Result
View All Result
  • Home
  • Business
  • Financial Planning
  • Personal Finance
  • Investing
  • Money
  • Economy
  • Markets
  • Stocks
  • Trading

Copyright © 2022-2024 All Rights Reserved
See articles for original source and related links to external sites.